PART 1 TITLE: My Husband Demanded That We Save Every Dollar, Then Announced a Luxury Vacation That Excluded Me and Our Children
The argument began with a pair of children’s shoes. My husband stood at the kitchen counter, holding the receipt between two fingers, while our daughter waited in the hallway with her backpack still hanging from one shoulder. He wanted to know why I had spent money without discussing it with him first. I explained that her old sneakers had worn through at the toes and that she had complained about her feet getting wet. He barely glanced at the shoes. Instead, he tapped the total printed at the bottom of the receipt and asked whether I understood how difficult it was to maintain a household when someone kept making unnecessary purchases.
I looked at our daughter. She had stopped pretending not to listen. Her eyes moved from the receipt to my face, and I could see her trying to decide whether she had done something wrong by asking for shoes. I told her to take her backpack upstairs and get ready for dinner. She obeyed without another word. Only after I heard her bedroom door close did I turn back toward my husband. I reminded him that children grew, clothing wore out, and some expenses could not be postponed simply because he disliked seeing money leave our account.
He folded the receipt neatly and set it beside his phone. He had a particular way of doing that whenever we disagreed. Everything about him became controlled: his hands, his expression, even the volume of his voice. He would speak slowly, as though explaining something obvious to a person incapable of understanding it. That evening was no different. He told me we needed discipline, that our future depended on the choices we made today, and that a family could lose its financial security through hundreds of small decisions nobody bothered to question.
I had heard those arguments so often that I could almost predict the order in which they would come. At the supermarket, I had begun checking unit prices more carefully than I ever had before. I planned our meals around weekly discounts, postponed replacing worn household items, and sometimes returned things to the shelves after reconsidering whether we truly needed them. My husband approved of these habits. He called them maturity. I called them compromises, though I rarely said that aloud. I believed our circumstances required them, and I was determined to contribute my share.
The strange thing was that he never provided a clear explanation of why our finances had become so restrictive. Whenever I asked whether our income had changed or whether an unexpected debt had appeared, his answers remained vague. There were expenses to manage, obligations to consider, and long-term plans that required sacrifices. He spoke confidently enough that I assumed he had examined numbers I had not yet seen. I handled much of the ordinary shopping and family organization, while he increasingly took charge of deciding which expenses were acceptable. It was an arrangement I had slipped into gradually, without noticing how little information I received in return.
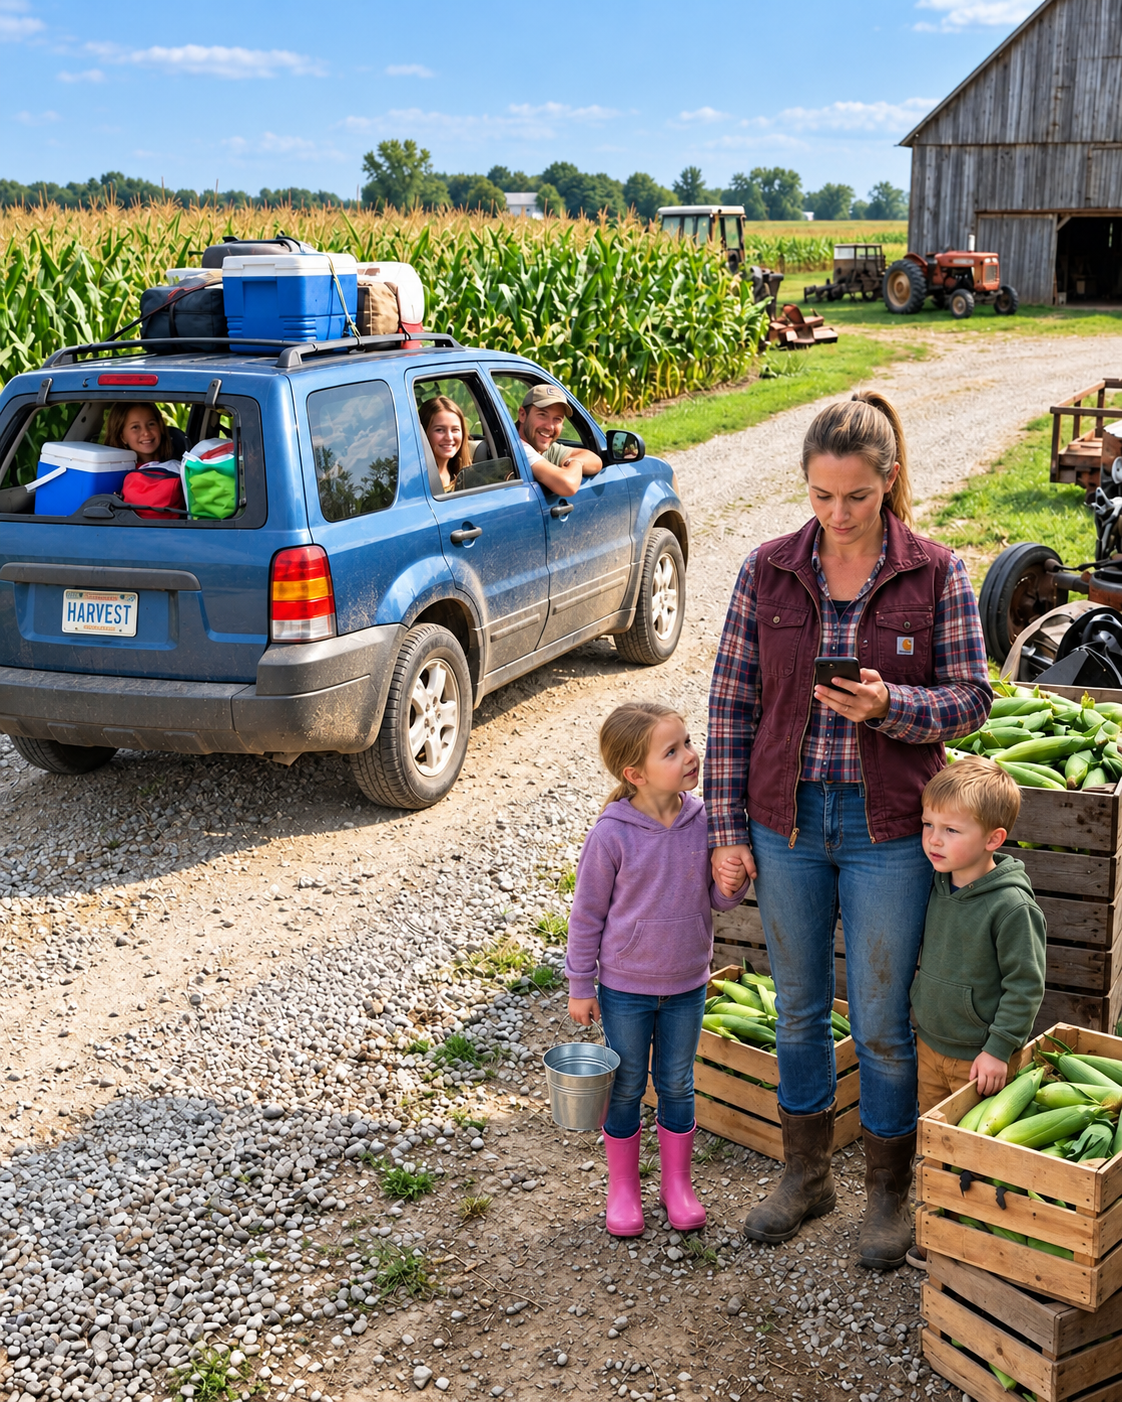
That evening, while I prepared dinner, my mother called. I wedged the phone between my shoulder and ear as I rinsed vegetables under cold water. She asked whether we could come to the farm over the weekend. The sweet corn was ready, and the harvest would require more hands than she and my father could comfortably manage alone. They could hire additional workers, she explained, but the cost would take a considerable portion of what they expected to earn. My father had been arranging crates and preparing the pickup, hoping the weather would remain favorable long enough to bring everything in.
I agreed without hesitation. Our children loved visiting their grandparents, and I knew the farm needed help. My parents had never treated family assistance as an obligation that required elaborate negotiations. When we needed someone to collect the children or help with a practical problem, they made room for us. When they needed an extra pair of hands, I tried to do the same. Their annual corn harvest was hard work, especially under the late-season sun, but it was also familiar. I could already imagine the smell of the fields, the dusty farmyard, and my father’s habit of checking every crate twice before loading it.
My husband was sitting at the table when I finished the call. I told him about the harvest and asked whether he could help with the heavier lifting. For a moment, he continued looking at his phone. Then he said he would not be available. I assumed he meant he had work to finish or an appointment he had forgotten to mention. When I asked what was keeping him busy, he answered that he was leaving for a vacation with his mother and younger sister.
I stopped beside the table with a dish towel in my hands. He said it as casually as someone mentioning an errand, although he had apparently organized an entire trip without telling me. I asked when they were leaving. The following morning, he replied. I asked when he had arranged it. He said the reservations had been made some time ago. Then he returned to his phone, as though the matter had been settled before I entered the conversation and nothing remained for us to discuss.
I pulled out the chair opposite him. There were several questions I wanted to ask, but the first one concerned money. Only minutes earlier, he had reprimanded me for buying necessary shoes. Now he was announcing a vacation that involved travel, hotel accommodation, restaurants, and whatever else his mother and sister intended to enjoy. I asked how the trip fit into the financial restrictions he had been imposing on our household. He looked up with an expression of weary impatience and told me not to turn everything into an argument.
I reminded him that he had been insisting for months that we could barely justify ordinary purchases. He replied that his mother deserved an opportunity to relax and that spending time with family was important. I did not dispute either point. His mother was entitled to enjoy herself, and he was free to value his relationship with her and his sister. What I could not understand was why the same financial standards did not seem to apply to everyone. When I asked whether he had set aside money specifically for this trip, he gave me no figure. He only repeated that everything had already been arranged.
The children entered the kitchen before I could answer. Our daughter took her place at the table, carefully avoiding eye contact with her father. Our younger child came in behind her, talking about an afternoon at school. I set the food down and tried to keep my voice ordinary. Dinner proceeded with the uncomfortable politeness that had become common whenever my husband and I disagreed. He discussed his travel plans with surprising enthusiasm, mentioning the hotel and the pleasure of getting away for a few days. Our daughter listened for a while before asking whether we would be going too.
He told her we had other plans. She frowned and said she thought the family was supposed to visit Grandma and Grandpa together. My husband explained that I would take the children to help with the harvest, while he accompanied his mother and sister. The division sounded perfectly reasonable when he presented it that way. He even suggested that working outdoors would be good for the children. I watched our daughter’s face as she considered this arrangement. She was old enough to recognize when adults were describing two very different experiences as though they carried equal rewards.
After dinner, he found me putting away the dishes. He said he wished I had not questioned him in front of the children. I pointed out that I had done nothing more than ask about plans he had concealed until the evening before his departure. He leaned against the counter and told me that I was making his desire to spend time with his mother sound selfish. I asked why we had not been included, especially when he knew the children would have liked a vacation as much as anyone. He answered that we were committed to the harvest and that a little physical work would benefit us.
There was something in the ease of his reply that troubled me more than the words themselves. He did not seem embarrassed by the contrast between our plans. His mother and sister would enjoy a comfortable hotel while I spent the weekend working beside my aging parents, with two children to supervise. He treated this difference as natural. When I asked whether he had considered helping at the farm before leaving, he smiled faintly and suggested that my father would surely manage without him. I could not remember when my husband’s obligations had become so flexible while mine were treated as permanent.
I wanted to challenge him further, but I knew the conversation would circle back to familiar accusations. He would say I resented his mother. He would claim I was trying to prevent him from enjoying himself. If I mentioned the money again, he would remind me of all the sacrifices he supposedly made for us. Eventually, we would be discussing my attitude rather than the decision that had caused the disagreement. I had begun recognizing this pattern, though I had not yet understood how much it had shaped our marriage. That night, I chose silence because I was tired of conversations in which nothing could be resolved.
Later, I helped the children prepare for bed. Our daughter sat on the edge of her mattress, pressing the toes of her new shoes against the floor. She asked whether Dad was angry that she needed them. The question landed more heavily than anything he had said during dinner. I sat beside her and explained that replacing shoes that no longer fit was a normal part of growing up. She wanted to know why he had sounded upset. I told her that adults sometimes worried about money and expressed those worries poorly. Even as I spoke, I wondered whether I was teaching her to excuse behavior I should have been challenging.
Our younger child was already asleep when I returned downstairs. The house had settled into its nighttime quiet, broken only by the low sound of the refrigerator and the occasional movement of a vehicle outside. My husband was packing. An open suitcase lay across our bed, and several neatly folded shirts rested beside it. He seemed entirely comfortable with his plans. I watched him select a jacket, examine it against the light, and put it in the suitcase. For someone who had spent months warning me about unnecessary expenses, he appeared remarkably unconcerned about the cost of his own trip.
I asked whether the hotel was expensive. He answered that it was a good place and that his mother would enjoy it. When I asked how long they were staying, he gave me a general answer rather than a precise schedule. I did not press him. There was no value in repeating the same argument while he packed. Instead, I gathered the children’s clothes for the farm, set aside their work shoes, and checked that we had enough clean water bottles for a long day outdoors. The contrast between our preparations was so obvious that I found myself avoiding the sight of his suitcase.
Before going to bed, I decided to review my credit card account. I had been postponing the task because the previous week had been busy, and I wanted to make certain every household expense was accounted for before the next payment became due. This was not an unusual habit. The card was in my name, opened independently, and I was responsible for the balance. I had always considered it important to monitor what I owed. My husband sometimes spoke about our finances as though every resource belonged equally to his decisions, but the credit account carried my name and my legal responsibility.
I took my laptop to the kitchen and opened the account website. The familiar dashboard appeared, showing the current balance and several account-management options. I expected to spend twenty minutes sorting ordinary purchases into categories. Instead, the balance gave me pause. It was higher than I expected. I checked the most recent transactions, looking for a payment that might not have posted or a purchase I had forgotten. Some entries were familiar, but several merchant names meant nothing to me. A hotel charge appeared among restaurant payments, and there were travel-related transactions that did not match any trip I had taken.
At first, I assumed I was overlooking something simple. A merchant sometimes appeared under a parent company’s name, and pending charges could be difficult to recognize without opening their details. I clicked through the transactions one by one. The unfamiliar entries remained unfamiliar. The dates were scattered over several weeks rather than concentrated around one event. Nothing suggested an accidental duplicate payment. I began paying closer attention to the information beside each charge, particularly the card identifiers. A few of the transactions did not match the card I carried.
I opened the account settings and looked for an explanation. The page contained the usual sections for statements, payment preferences, account security, and authorized users. I clicked the last option without much expectation. I knew my own card was active. I had never considered that someone else might be using additional cards linked to the same account. Yet the page displayed more than one cardholder. I read the first unfamiliar name, then the second, and felt my fingers become strangely cold against the keyboard.
The names belonged to my mother-in-law and my husband’s younger sister. I read them again, carefully checking the spelling because the information seemed impossible. Both women were listed as authorized users of the account for which I was financially responsible. I had not requested cards for either of them. Neither had approached me about borrowing credit, making travel arrangements, or sharing expenses. Until that moment, I had no reason to believe they possessed access to my account at all.
I pushed my chair back and stood. The kitchen suddenly seemed too small. I walked to the sink, turned on the tap, then shut it off without using the water. A question kept returning to me: how long had those names been there? My husband’s expensive vacation was beginning the next morning, and his mother and sister were the exact two people whose names had appeared on my account. The coincidence was too striking to ignore. Still, I knew that seeing their names did not tell me who had arranged the cards, what either woman had been told, or whether my husband was responsible.
I returned to the table and opened the account history. The transactions were no longer an assortment of puzzling charges. They were attached to additional cards, each identified by its own number. I selected the oldest available statement and began tracing the activity backward. One month’s charges led to another, then another. The dates reached far beyond the week of the planned vacation. This was not simply a last-minute arrangement for a hotel reservation. Whatever had happened, it had been happening while my husband insisted that I reduce the cost of groceries and postpone purchases for our children.
My first impulse was to wake him and demand an explanation. I could already imagine him standing beside the kitchen table, telling me I had misunderstood the arrangement. Perhaps he would claim it was temporary or insist that everything had been taken care of. I looked at the transaction list again. I had spent months accepting assurances instead of asking to see numbers. I was not going to repeat that mistake. Before I spoke to anyone, I needed to know exactly what the records showed and how far the spending extended.
I opened a blank document beside the account statements and began making notes. The house remained quiet upstairs. My husband was preparing to leave for a vacation he had described as perfectly reasonable, while I sat beneath the kitchen light looking at two names that should never have appeared without my knowledge. I realized that the next decision I made could change far more than our weekend plans. For the first time in months, I stopped asking whether I had been spending too much and began asking who had been spending money in my name.
END PART 1
PART 2 TITLE: Eleven Months of Hidden Charges Exposed a Financial Arrangement My Husband Had Never Once Asked Me to Approve
The first statement took several minutes to download. I watched the progress indicator while trying to remember whether my husband had ever mentioned opening additional cards. He had not. We had discussed household bills, payment deadlines, and the importance of protecting our credit, but I could recall no conversation in which I agreed to extend my account to his relatives. I searched my memory anyway, because the alternative was difficult to accept. If those cards had been issued without my knowledge, someone had made a decision involving my financial responsibility and then allowed me to continue believing I understood our circumstances.
I opened the document and examined the entries. The first unfamiliar charge was not enormous. It was a restaurant payment, the kind that might disappear among several weeks of ordinary spending if a person did not examine the statement carefully. Another appeared a few days later. Then came a hotel deposit, followed by additional dining expenses. None corresponded to places I had visited. The dates did not match family trips I remembered. I started recording each transaction associated with the extra cards, including its date, merchant, and amount. I wanted a record clear enough that nobody could dismiss it as a handful of mistaken purchases.
The second statement showed more of the same. There were travel-related payments, purchases from expensive businesses, and charges that suggested someone had been enjoying comforts I had repeatedly been told were beyond our budget. A single hotel stay might have been explained by an emergency or a special occasion. An occasional restaurant bill might have been connected to a celebration. But the entries continued, scattered through the months with an almost casual regularity. Whoever was using these cards had no apparent reason to believe the access would be questioned.
I moved backward through the account history, month by month. Some statements contained several unfamiliar transactions close together. Others showed smaller amounts distributed over longer periods. The frequency mattered as much as the cost. This was not one extravagant purchase that had slipped through a conversation. It was an arrangement that had survived repeated billing cycles, ordinary household arguments, and my husband’s lectures about restraint. Each statement represented another month in which he had been able to demand explanations from me while I remained unaware of activity under my own account.
The oldest relevant transactions reached back eleven months. I checked the dates twice. Nearly a year had passed since the first charges associated with those additional cards. I remembered that period clearly because it was around the time my husband had become especially concerned about our spending. He had suggested that we reduce unnecessary shopping and delay replacing items that were still technically usable. I had agreed because I believed we were working toward a shared financial goal. Now I was looking at evidence that a different kind of spending had continued alongside those restrictions.
I did not immediately add the figures. Instead, I looked for anything that might explain the arrangement fairly. There could have been reimbursements, transfers, or payments I had overlooked. Perhaps my husband had been covering the expenses in a way that was not obvious from the transaction list. I checked what the statements actually established and resisted turning uncertainty into an accusation. They showed additional cardholders and repeated spending. They did not tell me what promises had been made between my husband and his relatives. They also did not tell me whether either woman understood whose account she was using.
That distinction was important, though I was too upset to find much comfort in it. If my mother-in-law had been given a card and assured that her son would handle the cost, her understanding might be entirely different from mine. The same was true of my sister-in-law. I could not determine their knowledge from a list of transactions. But I did know that I had never been consulted, and that my husband had spent months behaving as though he alone had the authority to define responsible spending. Whatever explanation emerged, those two facts would remain.
I opened a spreadsheet and organized the charges by month. I entered the amounts slowly, checking each figure against the original statement before moving to the next. My first attempt contained an error because I had copied one restaurant payment twice. I found it when I compared the monthly subtotals, corrected it, and began checking the entire list again. I was determined not to confront my husband with a number he could discredit because I had been careless. If he challenged me, I wanted to place the statements in front of him and show exactly where the total came from.
The calculation finished while the clock above the stove moved toward midnight. I stared at the final figure: $18,731. I read it aloud, barely above a whisper. Eighteen thousand, seven hundred thirty-one dollars in charges associated with cards I had not knowingly provided. The total covered eleven months of activity. It was not an estimate based on how expensive the hotels looked or how much I imagined the restaurants might cost. It came directly from the records supplied by the credit card company.
I leaned back and looked toward the dark hallway. The amount was large enough to change how I understood the entire year. It represented more than individual purchases. It represented months of decisions I had made after being told that money was scarce. I had put things off, negotiated with myself in grocery aisles, and accepted that our children could not always have what they needed when they first needed it. My husband had praised me for becoming more careful. I had assumed that my restraint was helping protect our household. Now I wondered what it had actually been protecting.
I remembered standing in a supermarket with two packages of the same basic food, comparing the price per ounce while people moved impatiently around my cart. My husband had recently complained that our grocery bill was too high, and I had spent the next week looking for ways to reduce it without making the children notice. I had cut back on small conveniences, planned meals more rigidly, and stopped buying items that saved time but cost a little extra. At the time, I considered it an ordinary contribution to our family’s stability. Looking at the statements, I could no longer separate those sacrifices from the spending he had concealed.
The shoes returned to my mind. Our daughter had not asked for anything extravagant. Her old pair was worn, and I had replaced it. Yet my husband had treated the purchase as evidence that I lacked discipline. I pictured her in the hallway, trying not to look upset while he examined the receipt. What troubled me most was not that she had overheard us arguing about money. It was that she had begun to believe her basic needs were a burden. I wondered how many times I had allowed his version of financial responsibility to shape the way our children understood themselves.
I thought about asking him to come downstairs. His suitcase was packed, and he was sleeping only a short distance away. The questions were immediate. Why had he never told me about the extra cards? Why had he allowed spending to continue for eleven months? Had he intended to repay the charges? Did his mother and sister know the account belonged to me? I wanted answers so badly that I stood and walked toward the stairs. Halfway there, I stopped. He had controlled so many of our previous financial conversations by controlling the information available. I would not begin this one without preserving the records.
I returned to the computer and downloaded every relevant statement. I saved copies in a folder and gave the files simple names based on their dates. I also saved the page showing the authorized users and the identifying information associated with their cards. The process was ordinary, almost tedious, yet it steadied me. A few minutes earlier, the amount had seemed like a personal betrayal too large to examine calmly. Now I had documents that could be checked, questioned, and compared. Whatever he told me later, the underlying transactions would not change.
After saving the records, I examined the account-management options. The additional cards were still listed as active. That meant their holders could continue attempting purchases against the account, subject to its available credit and the issuer’s rules. My husband’s planned vacation was only hours away. I thought about the hotel deposits already visible in the records and wondered what other expenses might be planned for the coming days. If I did nothing, the total could continue growing while I tried to understand how the arrangement had begun.
I considered calling the credit card company immediately. There were questions about authorization that I could not settle by looking at the screen, and I knew I might need to speak with the issuer about how the cards had been requested. But one action was available to me without waiting for those answers. I could stop further use of the additional cards. I opened the relevant settings, selected the first card, and read the instructions carefully before submitting the request to freeze it.
For a moment, I hesitated with my finger above the keyboard. Freezing the card would almost certainly be noticed. It might interrupt a transaction, complicate someone’s travel plans, or provoke an argument before I had decided how to discuss the wider problem. I could already hear my husband accusing me of acting impulsively. Yet the alternative was to knowingly allow continued spending on an account for which I was responsible, simply because protecting it might upset people who had never asked my permission to use it. I confirmed the freeze.
I repeated the process for the second additional card. The account displayed the changed status. I checked both entries to make certain I had selected the correct cards and had not accidentally restricted my own. Then I returned to the transaction history. The previous charges remained, as they should. Freezing access did not erase what had already happened. It did not settle the existing balance, determine responsibility for past spending, or explain who had arranged the cards. It only prevented me from continuing to finance an unknown arrangement while I searched for the truth.
The simplicity of that action startled me. For months, my husband had made me feel that even small household expenses required complicated justification. Yet when faced with a financial decision that was genuinely mine to make, I had been able to act directly. I did not need to prove that our daughter deserved shoes or that our parents deserved assistance. I needed only to recognize my responsibility for the account and take reasonable steps to protect it. The contrast left me sitting in front of the screen long after both cards showed as frozen.
I began reconsidering the vacation. My husband had told me everything was booked, and he had spoken confidently about taking his mother and sister to an expensive hotel. Until that evening, I had assumed he was paying through resources I did not fully understand. Perhaps he had saved money separately, or perhaps his mother had contributed to the trip. Now I knew that additional cards in their names were attached to my account. I could not prove every planned expense would be charged there, but the possibility was no longer remote. The card history showed that travel and hotel spending had already occurred.
What disturbed me was how easily he had separated the consequences of his choices from the explanations he gave me. At home, he demanded restraint. With his relatives, he apparently presented himself as someone able to provide expensive experiences. I did not know whether his mother and sister appreciated how costly their spending had become. I did not know whether he had promised to cover every charge. I only knew that the account carrying the financial risk belonged to me and that I had been left outside the conversation.
I closed the spreadsheet but kept the statement folder ready. Then I sat in silence, listening to the house. The children’s bedroom doors were shut. My husband’s suitcase was waiting upstairs. Tomorrow, I would drive to the farm, where my parents were counting on us to help bring in their crop. He would head toward a comfortable vacation. Those plans had seemed unfair several hours earlier. Now the difference between them carried another meaning. I was expected to contribute physical labor because paid workers were too expensive, while he appeared prepared to enjoy travel paid for through an account I had not agreed to share.
I did not contact his mother or sister. The records showed the existence of the cards, but they did not establish what either woman had been told. Confronting them in anger might create accusations I could not yet support. I also decided not to call my husband while he slept. I wanted him to explain the arrangement, but I did not want another conversation in which he could dismiss each question before I had gathered my thoughts. For the moment, the account was secure, the records were saved, and I had time to decide what information I needed next.
I went upstairs and lay beside him without waking him. Sleep came slowly. Every time I closed my eyes, another ordinary memory appeared: a grocery receipt left on the counter, a household purchase postponed, a conversation about saving money that had ended with me apologizing. I thought about the accumulated total and wondered what repayment plan, if any, my husband had imagined. Had he believed he could replace the money before I noticed? Or had he grown so accustomed to controlling the household narrative that he assumed I would never examine the account closely enough to ask?
By morning, I was exhausted but certain about one thing. I would not unlock the additional cards simply because someone demanded it. I got up before the children, prepared breakfast, and organized what we needed for the farm. My husband came downstairs dressed for his trip. He was cheerful, moving around the kitchen with the easy confidence of someone looking forward to several days without responsibilities. He asked whether I had packed enough for the children and reminded me that working in the fields could be tiring. I answered his practical questions without mentioning the account.
At the door, he checked his phone and picked up his luggage. He seemed pleased with himself. His mother and sister were expecting him, and there was no suggestion that he intended to reconsider the division of our weekend. He told me to have fun with the harvest, then made another light remark about how a little honest work might do me good. I looked at him and wondered whether he had any idea what I had discovered during the night. If he did, he concealed it well.
I watched him place his suitcase in the car and drive away. The children were still finishing breakfast. I remained at the window until his vehicle disappeared from view, then returned to the kitchen and gathered our things. In my bag were the records of eleven months of hidden spending, including the $18,731 total and the names of the two additional cardholders. I had not accused anyone, and I had not yet demanded repayment. But the cards were frozen, and I had made a decision I would not reverse merely to preserve my husband’s comfort. If his vacation depended on access to my credit account, he was about to discover that the arrangement had changed.
END PART 2
PART 3 TITLE: While Our Children Worked Beside Their Grandparents, One Phone Call Revealed the True Cost of My Husband’s Luxury Vacation
The children were unusually quiet as we drove toward my parents’ farm. Our daughter sat by the window, watching the buildings give way to open land, while her younger sibling occupied the other side of the back seat. Normally, a visit to their grandparents brought a stream of questions about what they would do first and whether Grandpa would let them ride along while he moved things around the property. That morning, our daughter asked only whether Dad had reached the hotel yet. I told her he was probably still traveling. She nodded and returned her attention to the fields beyond the glass.
I knew she had noticed the difference between his departure and ours. Her father had left with a suitcase, clean clothes, and plans for a comfortable hotel. We were carrying old shoes, practical clothing, packed food, and water bottles. There was nothing shameful about helping with a harvest, and I did not want the children to think there was. My own childhood had been shaped by those fields, and some of my happiest memories involved working beside my parents. But I also knew the children could recognize when one parent treated work as an obligation for others and leisure as a privilege for himself.
The weather was already warm when we turned onto the road leading to the farm. The sun had climbed above the trees, brightening the rows of sweet corn that stretched across the property. Their leaves moved in the light breeze, making a dry whispering sound that I had known since childhood. Dust followed the tires as I approached the farmyard. My father’s pickup was parked near several stacks of crates, and he was arranging them with the concentration he brought to every task. He glanced up when he heard the car, then lifted one hand in greeting.
My mother came out carrying a jug of cold water and a small stack of clean cups. She had prepared sandwiches for later and placed them where they would remain out of the sun. She hugged the children first, asking whether they were ready to earn their lunch. Their spirits improved immediately. My father examined their shoes and reminded them to watch where they stepped. He had a way of giving instructions without making anyone feel foolish. He demonstrated what he wanted, explained why it mattered, and then trusted people to do their part.
My husband was not mentioned until my mother noticed that he had not come with us. I told her he was away with his mother and sister. She looked surprised, though she did not immediately question the decision. My father glanced toward the empty passenger seat of my car and then returned to his crates. After a moment, he asked whether the trip had been planned for some time. I said I had learned about it the previous evening. He studied my face briefly, as though considering whether to ask more, but all he said was that the work would be manageable with the help we had.
I was grateful for his restraint. The discovery on my credit account was still raw, and I was not ready to discuss it in front of the children. I wanted to understand what had happened before turning the matter into a family argument. At the same time, I felt the weight of carrying the information alone. The total of $18,731 had followed me through the night and into the morning. It was difficult to stand among familiar people and ordinary tasks while knowing that the financial arrangement within my marriage was far less ordinary than I had believed.
We began with the simplest work. My father showed the children how to carry the smaller baskets without dragging them across the ground. My mother supervised the sorting area, separating the corn that was ready to be packed from anything that required a closer look. I moved between the rows and the crates, helping wherever an extra pair of hands was needed. The work was repetitive but satisfying. Each basket filled, each crate stacked, and each cleared stretch of ground represented visible progress. Nobody needed a speech about responsibility. The work itself told us what remained to be done.
By midmorning, sweat had gathered beneath my collar. Fine dust clung to my shoes and the lower edges of my trousers. When I brushed a strand of hair away from my face, I left a faint streak of dirt across my cheek. My father noticed and smiled without commenting. He had spent too many seasons working outdoors to mistake clean clothing for evidence of useful effort. I thought of my husband’s remark about hard work doing me good. He had delivered it as though he were sending me toward an experience from which he had wisely exempted himself.
My daughter approached carrying a basket with both hands. She asked where she should put it, and I directed her toward the sorting area. Instead of leaving immediately, she looked at my face and asked whether I was tired. I told her I was, but that we were making good progress. She considered this, then said Grandpa had promised to show her how the crates were arranged in the pickup. I encouraged her to go. Watching her hurry toward him, I felt a familiar mixture of affection and anger. She deserved a childhood in which helping family was a source of connection, not a punishment for expenses she had never chosen.
As the morning continued, I found myself comparing my parents’ behavior with the financial rules at home. My father did not demand that we account for every minute of effort. My mother did not assign special importance to the person who carried the heaviest basket. They worked alongside us, adapted when someone needed a rest, and treated the children as willing participants rather than cheap labor. Their concern about hiring workers was practical. They wanted to preserve what the harvest earned. They were not using the need for savings as a reason to claim authority over someone else’s decisions.
I stopped briefly at the edge of the field to drink water. From there, I could see my parents working together without exchanging many words. My father lifted a crate before my mother had to ask. She moved another basket closer to him when she noticed he needed it. They had spent years learning the ordinary details of one another’s work. Their cooperation did not mean they always agreed, and I had witnessed enough family disagreements to know better than to imagine a perfect marriage. What struck me was that neither appeared to require the other’s ignorance in order to feel in control.
My phone rested in my pocket. Several times, I touched it without taking it out. I wondered whether my husband had already reached his destination, whether the hotel had requested payment, and whether anyone had tried to use the frozen cards. I had received no call from the credit card company and no message asking about the account. I reminded myself that freezing the cards was a precaution, not a test designed to catch someone. Still, I understood that the first attempt to use them could bring the concealed arrangement into the open.
I had thought carefully about what I would say if that happened. I would explain that I had reviewed the account, identified the additional users, and restricted their cards. I would ask who had authorized the arrangement and how the accumulated charges were supposed to be repaid. I would not agree to further spending until those questions had been answered. The plan sounded straightforward when I rehearsed it privately. But I knew from experience that my husband could turn a simple question into a challenge to his authority. I was less certain how calmly I would respond when he tried.
Around midday, my mother brought out the sandwiches. We sat where the shade offered a brief escape from the heat, with the children close enough to hear my father’s stories about previous harvests. He spoke about seasons when the weather had been difficult and others when the work went more smoothly than expected. The children asked questions, occasionally interrupting each other. Their grandmother reminded them to drink water and eat before returning to the field. For a little while, the sound of their conversation made the morning feel almost normal.
My mother watched me over the rim of her cup. She had known me long enough to recognize when my thoughts were somewhere else. After the children returned to their grandfather, she asked whether everything was all right at home. I told her there were financial matters I needed to clarify. She did not demand details. Instead, she asked whether I needed help. The question was so different from my husband’s usual response to my concerns that I had difficulty answering immediately. I told her I was not ready to explain but appreciated her asking.
She touched my arm briefly. Then she began gathering the empty cups, giving me the freedom to return to the work without further questions. I remained seated for another minute, looking toward the corn. My mother could be persistent when she believed something truly mattered, but she understood that asking a question did not entitle her to an immediate answer. My husband had often treated a delay in answering him as an act of defiance. I had grown so accustomed to defending ordinary decisions that being allowed to think felt unfamiliar.
When I returned to sorting, my father was loading another row of crates. The children were helping in small ways, moving baskets and checking that loose ears of corn were gathered. The afternoon promised more heat, but the work was proceeding steadily. I concentrated on the familiar movements: picking up an ear, checking its condition, placing it where it belonged. The rhythm gradually loosened the tension in my shoulders. I was beginning to believe I could finish the day before facing my husband, even if the account issue remained unresolved.
Then my phone rang. I recognized his name on the screen before I heard the second vibration. My first reaction was not surprise but a sudden tightening in my stomach. I stepped away from the sorting area and looked toward the children. They were busy with my father and appeared not to notice. My mother was arranging another basket several yards away. I moved far enough from them to speak privately, wiped my hand against my trousers, and answered.
He did not ask how the harvest was going. He did not ask whether the children were tired or whether my parents had enough help. His first words were an instruction to reactivate the card. He sounded irritated, but not yet worried, as though a minor inconvenience had interrupted an otherwise pleasant day. For a moment, I remained silent. I had prepared myself for a difficult conversation, but the abruptness of his demand surprised me. He assumed I would understand exactly what he wanted and act on it without requiring an explanation.
I asked him to identify the card. He responded that I knew perfectly well which one he meant. His mother’s card had been declined at the hotel, he said, and he needed me to remove the restriction immediately. I looked across the farmyard, where my father was helping our daughter reposition a basket. The scene seemed almost unreal beside the conversation unfolding through my phone. My husband’s mother was standing in an expensive hotel with access to a card attached to my account, while he expected me to resolve the payment problem from a field where our family was working.
I asked why his mother had a card connected to my credit account. It was a deliberate question. I already knew that her name appeared among the authorized users, but I wanted to hear how he described the arrangement. He hesitated before answering. Then he called it their travel card, using a phrase that made the matter sound routine and harmless. I asked whose account supported that travel card. He avoided the question and told me not to complicate the situation. The hotel needed payment, he said, and the immediate priority was getting the transaction approved.
I could hear voices behind him, though I could not make out their words. There was a brief pause while he apparently moved somewhere quieter. When he returned, his impatience had sharpened. He said the hotel staff were waiting and that he could not stand there debating something so simple. I asked how much they were trying to charge. He answered quickly, as though the number should settle the matter: $4,800.
I looked down at my dusty shoes. Four thousand eight hundred dollars. The amount was so far removed from the household purchases he had criticized that I needed a moment to absorb it. I thought about the worn sneakers, the groceries I had put back on shelves, and the repeated warnings that we had to control our spending. Then I imagined a hotel requesting nearly five thousand dollars from a card attached to my account. I asked what the payment covered. He said it was for the hotel and repeated that he needed the card unlocked.
The figure gave the discovery from the previous night an immediate consequence. The $18,731 represented charges already recorded over eleven months. This was a new payment they wanted to make while the additional cards remained frozen. I did not know exactly how the hotel had structured the bill or how much had already been reserved through earlier transactions. I did know that authorizing another $4,800 would allow the arrangement to continue before my husband had explained a single part of it.
He told me that his mother was embarrassed because the payment had been rejected. I understood that a declined card could be upsetting, especially when someone believed the funds were available. But the embarrassment did not answer my questions. If she had been told the card was hers to use, perhaps she was genuinely confused. If my husband had assured her that he was paying, perhaps she had no idea why the transaction failed. Those possibilities mattered. None gave him the right to order me to accept another charge without discussion.
I asked whether he had another way to pay. He sounded offended. The room was expensive, he said, and he had already made arrangements. I asked what arrangements he meant. He began talking about the importance of treating his mother properly and how difficult it would be to change plans at the last minute. His explanation contained plenty of urgency but no answer about the source of the money. I realized that if I continued following his arguments, I would soon be defending myself against the accusation that I had ruined his mother’s vacation.
I moved farther from the children and stood near the edge of the field. The dry leaves shifted in the breeze, brushing together with a sound that briefly covered his voice. I told him that I had reviewed my credit account and that the additional cards were frozen. He asked why I had done that without consulting him. The question was so revealing that I almost laughed. He expected to be consulted before I restricted spending on an account he had never consulted me about sharing.
I explained that I was responsible for the account and had discovered activity I could not identify. He interrupted, saying that this was not the time for a financial argument. I replied that the time had become unavoidable because he was standing at a hotel requesting another substantial payment. He insisted that I was making a problem out of something that could be resolved in seconds. All I had to do, he said, was reactivate the card. We could discuss everything after the vacation.
That suggestion brought back the previous evening, when he had asked me not to start an argument about money because the trip was already booked. He had presented the completed reservation as a reason not to question the expense. Now he was presenting the hotel’s immediate demand as a reason not to question the payment. The circumstances changed, but the expectation remained the same: I was supposed to accept a decision after he had made it, then absorb the consequences because objecting would be inconvenient.
I asked him one final time whether he could explain why his mother had been using my credit account. He said he would explain later. I told him later was no longer sufficient. My voice remained quieter than I expected. I was standing in the middle of a working farm, tired and dirty, but I had the account statements saved and the transactions written down. I did not need to argue about whether $4,800 was a reasonable hotel expense. I needed to decide whether I would permit it to be charged against an account I was responsible for.
He repeated the instruction to unlock the card. I looked toward the children, who were helping their grandfather move another basket. My daughter caught my eye and waved. I lifted my hand in response. Then I turned slightly away so she would not see my expression. My husband waited on the phone, apparently certain that persistence would eventually wear down my objections. I told him I would not authorize the payment.
He fell silent. For several seconds, I could hear only the faint movement of people around him and the rustle of corn behind me. Then he asked whether I was serious. I said that I was. He warned that refusing would create a humiliating situation for his mother and sister. I told him I understood the inconvenience but would not expose my account to another charge without knowing how the existing spending had been arranged. His breathing changed, and I recognized the moment when he stopped trying to persuade me and began preparing to blame me.
I held the phone away from my ear for an instant, then brought it back. I had spent months modifying ordinary decisions to avoid his displeasure. I had apologized for purchases that needed no apology and accepted financial rules whose purpose I no longer understood. This time, the evidence was in my possession, the account was under my responsibility, and the decision belonged to me. The hotel could demand payment, my husband could insist, and his relatives could be disappointed. None of those things would make me unlock the card.
END PART 3
PART 4 TITLE: I Refused the Hotel’s Four Thousand Eight Hundred Dollar Charge, and My Husband Returned Home Demanding an Explanation
My husband’s anger arrived suddenly. He raised his voice and accused me of abandoning his mother at an expensive hotel without a way to pay. The accusation might have frightened me on another day. I would have imagined her standing at the reception desk, embarrassed and uncertain what to do, and I would have rushed to correct the situation before anyone became more upset. But this time, I understood what was actually happening. His mother was not alone in an unfamiliar place. She was traveling with her adult son and daughter, and the three of them were capable of making arrangements that did not involve charging thousands of dollars to my credit account.
I told him exactly that. He responded that I had no idea how humiliating the situation had become. The hotel expected payment, his mother was distressed, and he had been forced to explain why the card would not work. I asked whether he had explained whose account supported it. He ignored the question and accused me of deliberately creating a scene. I looked across the farmyard at my parents, who were still working in the heat, and found it difficult to understand why his embarrassment deserved more attention than the money he had been spending without telling me.
He said I was making him look irresponsible in front of his family. That was the first thing he said that made me genuinely angry. For months, he had treated me as though I were the person who could not manage money. He had questioned grocery bills, postponed necessary purchases, and reminded me that every dollar mattered. Now he was asking me to protect his reputation by allowing another expensive charge to proceed. I told him that refusing to authorize spending was not what had placed him in this position. His decision to rely on an account without discussing it with me had created the problem.
There was a pause, followed by a quieter question. He wanted to know how much I had seen. The change in his tone was unmistakable. Until that moment, he had spoken as though the frozen card were an unexpected inconvenience. Now he sounded concerned about what I understood. I told him I had reviewed the transaction history for both additional cards. I had downloaded the statements and checked the activity across eleven months. I heard him shift his position, and the background noise grew quieter. He was listening more carefully than before.
I gave him the total: $18,731. I explained that the figure came from transactions associated with the additional cards and did not include the new $4,800 hotel payment that had just been declined. I did not raise my voice or ask him to imagine how many household purchases the money could have covered. The number was substantial enough without embellishment. He did not answer immediately. I waited, holding the phone against my ear while the wind moved through the corn beside me. His silence confirmed nothing about who had authorized the cards, but it told me that the amount was not a surprise to him.
When he finally spoke, he said they had intended to repay the money. I asked when that repayment was supposed to happen. He replied that I was missing the important point. I asked him to identify it. He said the expenses had been managed as part of a family arrangement and that there had never been any intention to leave me responsible. I wanted to know what arrangement he meant, who had agreed to it, and why I had not been informed. He offered no dates, no payment schedule, and no explanation of how the cards had been issued.
I reminded him that I was the account holder. Whatever he had planned privately, the financial obligation attached to the account was mine. He said that marriage meant sharing resources, a statement I would normally have agreed with. But sharing required knowledge and consent. We had not discussed extending my credit to his relatives, and I had not approved eleven months of expenses. I told him that a promise to repay money did not explain why the money had been spent without my permission. He became impatient again and said that I was focusing on technicalities rather than the spirit of helping family.
I looked toward my parents. My father was struggling to position a crate against the others in his pickup, and my mother moved closer to steady it. Neither waited for the other to ask. They were doing the work together because they had agreed it needed to be done. I thought about my husband’s description of family support and how selectively he applied it. He believed his mother deserved an expensive vacation, but my parents apparently deserved help only from the people he was willing to send. He considered my credit available to his relatives, yet treated basic expenses for our children as matters requiring his approval.
I told him that I had no objection to helping family when the help was discussed honestly. If his mother had needed assistance, we could have examined our finances and decided what we could afford. If his sister had an expense she could not manage, we could have considered whether a loan or contribution was appropriate. That would have been a family decision. What I could not accept was the discovery that additional cards had been used for nearly a year while I was being instructed to reduce our children’s expenses. He answered that I was exaggerating the situation.
I asked which part was exaggerated. The additional cardholders were listed on the account. The statements showed the charges. The total was calculated from those statements. The cards had been used repeatedly over eleven months. Every one of those facts could be checked. He said I was treating him like a stranger and suggested that my lack of trust was becoming the real problem. I found the accusation almost impossible to believe. He had concealed information that directly affected my finances, and now he wanted me to apologize for having discovered it.
I told him trust was precisely why the situation mattered. I had trusted his warnings about money. I had accepted that we needed to be careful, even when I could not see a clear explanation for the restrictions. I had believed we were making sacrifices together. The statements suggested otherwise. He could not insist that I trust his judgment while refusing to disclose decisions he had already made. He interrupted to say that he had always intended to handle the payments. I asked why, if that was true, he had never mentioned the arrangement. He did not answer.
For several seconds, neither of us spoke. I heard someone near him ask a question, but his reply was too quiet for me to understand. Then he returned to the call and announced that we would discuss the matter when he got home. I agreed. There was a great deal to discuss, and I wanted that conversation to take place with the account statements available. He seemed relieved for an instant, as though agreeing to postpone the discussion meant the immediate problem had disappeared. Then he told me to reactivate the card so the hotel could complete the payment.
I refused again. This time, there was no hesitation. He reminded me that his mother was waiting and that they could not simply leave the situation unresolved. I told him he and his sister were responsible adults who could work with the hotel to arrange payment. I would not unlock the card before the existing charges had been explained. He said something sharp about my stubbornness, then ended the call without saying goodbye. I stood with the phone in my hand, looking at the disconnected screen, and realized that he still had not answered the simplest question I had asked: why had he never told me?
I returned the phone to my pocket and remained beside the field for a moment. The silence after his anger felt almost physical. My heart was beating harder than I wanted to admit, and my hands were trembling slightly. I had expected him to be upset. What I had not expected was how confidently he would demand more access after learning that I knew about the previous spending. He seemed to believe that the urgency of the hotel bill should outweigh everything I had discovered. I was beginning to understand that my willingness to avoid conflict had become something he counted on.
My mother approached carrying an empty basket. She looked at my face and asked whether something had happened. I told her that a financial problem at home had become more serious than I expected. She studied me for a moment, then glanced toward the children. I knew she wanted to ask more, but she understood why I did not want to explain everything there. She handed me the basket and said we could talk when I was ready. The gesture nearly undid me. She had noticed my distress and offered help without demanding control of the situation.
We returned to work. I was grateful for the physical effort because it gave my body something to do while my thoughts settled. My father continued loading crates, and I helped position them securely. The children carried smaller baskets from the sorting area, proud whenever their grandfather told them they had done something correctly. I watched them move between my parents and remembered why I had wanted them to spend the day here. They were learning that helping someone did not require a performance of generosity. It required paying attention and doing what was needed.
The afternoon grew hotter. We took short breaks for water, then returned to the remaining corn. My husband did not call again. I checked my phone only occasionally, resisting the temptation to anticipate his next accusation. The account remained frozen. Nothing he had said changed the facts I had recorded, and I could not responsibly authorize new charges because he had become angry. There was still an existing balance to address, and I would eventually need a clear explanation of how the extra cards had been requested. But those questions would have to be answered through records and honest conversation, not through another hurried demand.
As the work continued, I considered what his mother and sister might know. His claim that they planned to repay the charges suggested some arrangement existed, but it was impossible to determine its terms from his words. He had called the additional card a travel card. Had he given his mother that same description? Did she believe he paid the balance himself? Had his sister understood the account belonged to me, or had she accepted whatever explanation her brother provided? I could not assume either woman was innocent, but I also could not fairly accuse them without hearing their accounts.
I remembered family gatherings during the previous year. My mother-in-law had spoken about pleasant meals and comfortable places she had visited. My sister-in-law had occasionally mentioned travel plans. At the time, I had not paid much attention to the financial details because I assumed they managed their own expenses. I had never asked who paid for a restaurant or whether a hotel reservation was charged to a particular card. Now those ordinary conversations seemed connected to the statements on my computer. I was careful not to treat every memory as evidence. What mattered was that I finally had a reason to ask questions.
My father’s pickup was nearly loaded when we heard a vehicle approaching along the farm road. I expected another delivery or someone passing through. Then I recognized the car. My husband had returned, bringing his mother and younger sister with him. Their vacation had ended far sooner than they had planned. I watched the car cross the yard and stop near the place where we were stacking crates. For a moment, nobody moved. My husband remained behind the steering wheel, while his mother sat looking straight ahead. His sister turned toward him as though asking something, but I could not hear her words.
He climbed out first. The expression on his face told me that the journey back had not improved his mood. His mother followed, looking tired and uncomfortable, and his sister emerged a moment later. Neither woman appeared eager to begin an argument. My husband, however, crossed the farmyard with quick, deliberate steps. I was standing beside my father with dirt on my hands and an unfinished crate at my feet. He stopped in front of me and said we needed to discuss what I had done. I put down the corn I was holding and brushed my palms against my trousers.
I asked him to explain what he wanted to discuss. He glanced toward my parents and then toward the children, who had stopped working to watch. He said the conversation should take place somewhere private. I understood the concern about speaking in front of the children, and I did not want them drawn into the disagreement. My mother quietly called them over and directed their attention toward another basket. They remained close to their grandfather, occupied with the harvest. But I was not willing to let my husband exclude the two women whose names appeared on my account.
I told him that his mother and sister needed to hear the explanation as well. He said I was making a private financial disagreement unnecessarily public. I replied that the disagreement involved cards issued in other people’s names and charges those cards had accumulated. The people involved deserved accurate information about what had happened. He looked toward his mother, perhaps expecting her to support his request for privacy. Instead, she stepped closer. Her expression was troubled, but she seemed prepared to listen.
There was a brief, awkward exchange as my mother-in-law approached me. She had a credit card in her hand. She held it out, and I accepted it without speaking. I recognized it as the additional card that had been declined at the hotel. Holding it made the situation feel different from examining the account online. The plastic was ordinary, no heavier than the card I carried myself, yet it represented months of spending that had affected my financial responsibility without my knowledge. I turned it over once, then looked at my husband.
He began telling me that the hotel incident had been unnecessary and that we could have resolved everything without forcing them to return. I asked him to stop talking about the inconvenience of the trip and explain the card. He insisted that the situation was complicated. I told him the first question was simple enough. I raised the card slightly so his mother could see it and asked whether she understood that it was connected to a credit account held in my name.
She frowned. At first, she seemed uncertain she had heard correctly. Her eyes moved from the card to my face, then to her son. I repeated the question, making clear that I was not asking whether she had used the card. The statements already showed that activity. I wanted to know what she believed about the account itself. My husband opened his mouth, but his mother lifted a hand and asked him to let her answer.
She told me that her son had presented the card as a way to cover their travel expenses. According to her, he had said he would take care of the payments. She had understood that the arrangement was his responsibility. I watched her carefully. Her surprise appeared genuine, though I knew I still needed to hear the full explanation. My husband shifted his weight and said she was making the situation sound worse than it was. His mother turned toward him and asked why he had never mentioned that the credit belonged to his wife.
He tried to interrupt. She continued looking at him. The question was no longer coming from the person he had accused of being jealous, difficult, or financially unreasonable. It was coming from the mother whose vacation he had been so determined to protect. She wanted to know why he had given her a card without explaining who would be responsible for the charges. He said again that he intended to manage the payments, but she shook her head. Managing a payment, she told him, was not the same as owning the account or having permission to use it.
I looked toward my sister-in-law. She was standing a short distance away, listening intently. I could not tell whether the information was new to her or whether she was worried about what would be revealed next. My husband’s attention moved between us, searching for a way to regain control of the discussion. I realized then that we had all arrived at the farmyard with different understandings of the same financial arrangement. My husband had been the person connecting those understandings, and none of us had previously compared what we had been told.
His mother took one step toward him. Her voice was low but clear enough for everyone nearby to hear. She asked whether he had really allowed her to spend against my credit account for months while letting her believe that he was paying the expenses himself. My husband looked down at the ground. He did not immediately answer. I held the returned card in my hand and watched his mother wait for a response. The statements had shown me where the money had gone. Standing in the farmyard, I was beginning to discover how he had persuaded everyone else that the arrangement was something entirely different.
END PART 4
PART 5 TITLE: When the Hotel Call Ended, the Quiet Rows of Corn Left Me With a Decision No One Else Could Make
The call ended without a goodbye. I stood beside a stack of wooden crates, holding my phone against my palm while the afternoon heat settled over my shoulders. Somewhere behind me, my father was explaining to our son how to tell whether an ear of sweet corn was ready to pick. The familiar sounds of the farm continued around me, but I could still hear my husband’s voice demanding that I restore access to the card. He had sounded less concerned about the money than about being told no.
I slipped the phone into my pocket and picked up the basket I had abandoned. The handle had worn a red mark into my fingers earlier that morning. I carried it toward the sorting table, where my mother was removing loose husks and arranging the finished ears into neat piles. She glanced at me, then at the phone-shaped outline against my jeans. She had heard only fragments of the conversation, but she knew me well enough to recognize when something had gone badly.
“Do you need to leave?” she asked. I shook my head and set the basket down. “No. I need to finish what I came here to do.” She studied my face for another moment, apparently deciding whether to press. Instead, she moved a pitcher of lemonade into the shade and pushed a clean glass toward me. The gesture was so ordinary that it almost undid me. Nobody had asked what the lemonade cost, whether it was necessary, or why I hadn’t chosen something cheaper.
For eleven months, I had accepted my husband’s insistence that our household needed stricter financial discipline. At first, his arguments had sounded reasonable. Prices were rising, unexpected expenses could arrive at any time, and we had two children whose needs would only become more expensive. I had responded by making careful adjustments. I changed grocery stores, delayed replacing worn clothing, postponed a routine appointment, and learned to make the contents of our refrigerator last another day whenever possible.
He had never described those sacrifices as temporary. Each time I found another way to economize, he treated it as proof that I could have been spending less all along. A receipt containing something he considered unnecessary could sour an entire evening. Once, when I bought our daughter a pair of shoes because the soles of her old ones had started separating, he examined the price tag before asking why I hadn’t waited for a clearance sale. I remembered standing in the kitchen with the shoes in my hand, trying to explain why waiting wasn’t possible.
Yet the statements I had examined the night before told a different story about our family finances. While I had been cutting coupons and calculating the cost of school lunches, additional cards connected to my personal credit account had paid for restaurants, lodging, transportation, and expensive purchases. The transactions stretched across eleven months. I had totaled the charges twice, then once more with a calculator, because the amount seemed too large to belong to the life I thought we were living. Eighteen thousand, seven hundred thirty-one dollars.
The figure had not changed when I checked it again that morning. Neither had the account information. My mother-in-law and my husband’s younger sister were listed as authorized users. Their names appeared on cards tied to an account I had opened independently, an account for which I remained financially responsible. I had never discussed adding them. I had never agreed to finance their travel. Most troubling of all, I had not known the arrangement existed until the evening before my husband departed for his vacation.
I watched our children working beside their grandfather. Our son was carrying a basket that was almost too wide for him, carefully balancing the ears so none would roll out. Our daughter had tied her hair back with a faded ribbon and was inspecting each ear as seriously as if she had been appointed the farm’s quality-control manager. They were hot, dusty, and happy. Neither had any idea that their father had just demanded another $4,800 from an account their mother was responsible for paying.
My father called for another crate, and I carried one over. He thanked me without looking up. That was how things worked here. People noticed what needed doing, and they did it. When the farm required extra hands during harvest, my parents asked us to help because hiring more workers would strain their budget. They didn’t pretend the work was glamorous. They offered lunch, cold water, and a place to rest when the heat became too much. They had never suggested that helping them entitled anyone to unlimited access to somebody else’s money.
Another message appeared on my phone. My husband had written that the hotel was holding the reservation and that his mother was upset. He said I needed to stop being stubborn before I ruined the entire trip. I read the message twice. Nothing in it addressed the eleven months of charges. Nothing explained why two additional cards had been issued or who had arranged them. His immediate concern was still the payment he wanted me to approve, not the account he had concealed.
I typed a response and erased it. The first version was angry, filled with questions I had been holding since I discovered the statements. The second was too long. Eventually, I wrote that the cards would remain blocked and that I would discuss the existing charges after he returned. I added that he, his mother, and his sister were adults who could make alternative payment arrangements. Then I put the phone away before I could spend the next hour waiting for his reaction.
My mother came beside me as I reached for another basket. “Was that about his trip?” she asked. I nodded. She pulled a loose strand of hair away from her face and waited. I told her he had reached the hotel and encountered a problem with a credit card. She didn’t immediately offer an opinion. Instead, she asked whose card it was. The question seemed almost painfully simple. I told her it was mine, and that I had discovered two other people were using it without my knowledge.
She stopped working. The ear of corn in her hand rested against the edge of the table. “Without your knowledge?” she repeated. I explained that the statements covered nearly a year and that the charges were substantial. I did not list every transaction or describe every argument my husband and I had had over money. My mother could see enough from my expression. She looked toward the children before speaking again. “Does he understand that you’re the one responsible for that balance?” I answered that he understood perfectly well.
She lowered her eyes to the table. For a moment, I thought she would tell me what to do, but she only said, “Then he needs to explain himself.” I had spent so many months being treated as unreasonable for questioning ordinary expenses that hearing someone describe the situation without defending him was unexpectedly difficult. My mother didn’t call him names. She didn’t tell me my marriage was finished. She recognized that a serious problem existed and that the person responsible needed to account for it.
At lunchtime, we gathered beneath the broad shade beside the packing shed. My father brought out sandwiches wrapped in waxed paper, and the children argued cheerfully over who had carried more baskets. I ate slowly, listening to the ordinary conversation around me. Our daughter wanted to know whether she could bring some corn home for dinner. Our son asked if the pickup would be loaded before sunset. I answered them both while trying not to think about the balance waiting on my next statement.
My husband called again while we were putting away the lunch dishes. This time I walked toward the end of the gravel lane before answering, far enough from the children that they wouldn’t hear. He began by telling me the hotel staff were being difficult. They wanted the outstanding amount settled before continuing with the reservation. I asked whether he had another card. He said he did, but he didn’t want to put such a large expense on it. The words stayed with me.
“So you don’t want that charge on an account you’re responsible for,” I said. He made an impatient sound and told me I was twisting his meaning. I asked what he meant instead. He said the account had always been useful for family travel and that I was suddenly treating an ordinary arrangement as a crime. I reminded him that I hadn’t known about the arrangement. His answer was that he handled the payments. I told him handling something and telling the person who owned it were not the same thing.
He switched to a softer voice. He said his mother had been looking forward to the vacation, that his sister had taken time away from work, and that everyone had already traveled a considerable distance. I could hear the murmur of voices behind him and the faint mechanical sound of an elevator. He wanted me to imagine the inconvenience they were experiencing. I did imagine it. Then I remembered our daughter waiting weeks for new shoes while I tried to satisfy his rules about spending.
“I didn’t cancel your trip,” I told him. “I stopped an account from being used without my permission.” He replied that I knew perfectly well those two things had the same practical result. I said the hotel accepted other methods of payment. He insisted I was missing the point. I stood on the gravel, looking at the pale dust clinging to my shoes, and realized that the point had become impossible to miss. He wanted to preserve his convenience even after I had discovered what it cost me.
I asked him how the cards had been requested. For the first time during the conversation, he didn’t answer immediately. He said he had taken care of it months ago. I asked whether he had used my login information. He told me not to turn a family disagreement into an interrogation. I repeated the question. His silence lasted long enough that I heard somebody call his name in the background. Then he said we would discuss the technical details when he got home.
Technical details. That was how he described the possibility that another person had arranged spending privileges on my account without my knowledge. I did not argue over the phrase. I told him I had saved the statements and would be checking with the card issuer about the account history. His tone changed at once. He asked whether I was trying to get him into trouble. I answered that I was trying to understand how my account had been used. He said I was making everything unnecessarily official.
After the call, I stayed beside the lane until my breathing settled. I wasn’t accustomed to ending a disagreement without either apologizing or promising to reconsider. With my husband, arguments about money usually concluded when I agreed to explain myself more carefully the next time. He could turn almost any conversation into a review of my shortcomings. Today, however, he had been asked straightforward questions and had chosen not to answer them. I couldn’t make that choice for him, and I no longer intended to excuse it.
I returned to the packing shed and found my father loading the final crates from the morning’s picking. He noticed that I was quieter than usual and asked whether anything was wrong at home. I told him enough to explain the problem, careful not to repeat details that involved the children. He listened while tightening a strap across the truck bed. When I finished, he rested one hand on the tailgate. “If someone wants to borrow a tractor,” he said, “they ask the person who owns it. Money shouldn’t be more complicated than that.”
His comparison was imperfect, but I understood the principle. My father had spent his life keeping equipment running and accounts balanced. He knew how easily a small debt could become an enormous one if people ignored it. He also understood that borrowing something carried an obligation to return it in the condition agreed upon. My husband had never offered me the chance to accept or reject what had happened. He had simply decided, then expected me to live with the consequences.
Later that afternoon, I checked the account from my phone. Both additional cards remained frozen. The existing charges were still there, but no further purchase had appeared. I saved another copy of the transaction history and the list of authorized users. I also made a note of the time my husband had called and the amount he had requested. I wasn’t preparing a public accusation. I wanted a clear record, because I had already seen how easily he could turn specific questions into arguments about my attitude.
My daughter came over while I was closing the banking page. She held up an ear of corn with several pale kernels missing near the tip. “Grandpa says this one isn’t good enough for the market,” she announced. I told her it would still be good to eat. She smiled, apparently pleased that something rejected for one purpose could remain useful for another. Then she looked at my face more closely. “Are you mad at Dad?” she asked.
I considered the question before answering. I told her that her father and I were having a disagreement about something important, but that it was an adult matter and she did not need to fix it. She nodded without appearing entirely satisfied. Children notice tension long before adults choose to explain it. I brushed a loose piece of silk from her shoulder and asked if she wanted to help me fill another crate. She took my hand, and we walked back toward the table.
By late afternoon, the farmyard smelled of cut stalks, warm earth, and the damp towels my mother had laid over baskets of freshly picked corn. My back ached from bending, and my arms felt heavy. There was still work remaining, but the urgent part of the harvest had gone well. My parents were discussing the next day’s deliveries. The children were drinking cold water beneath the shade. I was beginning to believe the rest of the day might pass without another confrontation.
Then my phone vibrated. My husband had sent a message saying the trip was effectively over and that he was coming back. He wrote that we needed to settle this before I embarrassed him any further. I reread the words. He had not said he was sorry. He had not offered to explain the account or the charges. He was returning because his plans had become inconvenient, and he believed I was responsible for that inconvenience.
I showed the message to my mother. She read it without comment and handed the phone back. My father was a few steps away, checking the crates. I told him that my husband might stop by the farm before we finished. He asked whether I wanted the children occupied elsewhere. I said yes. There was no reason for them to stand in the middle of an argument about spending they had never authorized and could not possibly understand.
My mother took them toward the kitchen with a promise that they could help prepare corn for supper. I watched them go, their voices fading past the screen door. Then I turned back toward the yard, where the baskets and crates still waited. I knew my husband would want a private conversation. In private, he could tell me I had misunderstood. He could suggest that I was jealous of his mother, that I had overreacted, or that I should think about the embarrassment I had caused.
But the names on the account were not a private misunderstanding between two spouses. Two other adults had received cards connected to my credit, and I needed to know what they had been told. The statements showed where the money had gone, but they could not reveal whether his mother and sister believed they were using his funds. Until I heard their accounts, I would be guessing. I had spent enough time accepting my husband’s explanations without checking them.
I moved a small stack of crates away from the center of the yard and wiped my hands on a towel. A vehicle turned off the road in the distance, raising a thin cloud of dust along the lane. My father’s pickup remained parked beside the shed. I recognized the approaching car before I could see the occupants. My husband had returned, and from the speed at which he entered the drive, it was clear he expected the conversation to begin on his terms.
I set the towel down, glanced once toward the kitchen where the children were safely occupied, and walked into the open yard. My husband’s car stopped beside the packing shed. Three doors opened. He emerged first, followed by his mother and younger sister. He looked directly at me, already shaking his head as though I had disappointed him beyond explanation. I stayed where I was. For the first time in eleven months, I had the records, the questions, and no intention of letting him decide which ones could be asked.
END PART 5
PART 6 TITLE: Three People Returned From the Ruined Vacation, but Only One of Them Seemed to Know Whose Money Had Paid for Everything
My husband shut the car door harder than necessary. His mother climbed out from the passenger side with her handbag tucked beneath one arm, while his younger sister stepped out behind her, carrying a small travel bag. None of them looked rested. The vacation clothes that had seemed so carefully chosen when they left that morning looked strangely out of place beside the crates and muddy tires. My husband crossed the yard without acknowledging my father, who stood near the pickup with a pair of work gloves in his hand.
“We need to talk,” he said. His face was flushed, although the car’s air conditioning had been running. I asked what he wanted to discuss. He looked past me toward the packing shed, then lowered his voice. “Not here. We can go home and sort this out like adults.” I told him I was willing to talk but wasn’t leaving the farm to do it. His eyes narrowed. “You always have to make things difficult when my family is involved.”
I might once have answered that accusation by reminding him how often I welcomed his relatives into our home. I might have listed the birthdays I organized, the meals I cooked, and the errands I handled when his mother needed help. I would have been defending myself against a question nobody had actually asked. This time I said nothing about my previous efforts. I asked him why his mother and sister had been given cards connected to my personal credit account.
His mother stopped adjusting the strap of her handbag. She looked from me to him, then back again. My husband answered quickly, saying the cards had been issued for travel expenses and that everybody knew about them. I pointed out that I hadn’t known, despite being the account holder. He gave a short, irritated laugh and said I was pretending not to understand how families shared expenses. The ease with which he described the arrangement made me wonder how often he had rehearsed the explanation.
His sister moved closer to the car. She appeared uncomfortable rather than angry, though I couldn’t tell whether that was because of the confrontation or the interrupted vacation. “Can we just get out of the sun?” she asked. I told her the shade beside the packing shed was cooler. My father quietly moved two empty crates away from the benches, making room without inserting himself into the discussion. My husband watched him for a moment and then turned back to me.
“Do you see what you’re doing?” he demanded. “You’re dragging your parents into our marriage.” I told him my parents were there because it was their farm, not because I had invited them to take sides. The issue wasn’t their presence. It was the account. He said again that he had intended to pay everything back. I asked whether he had established a payment schedule. He hadn’t. I asked whether he had already made any payments specifically covering the additional cards. He gave no clear answer.
My mother-in-law stepped beneath the shade, set down her handbag, and asked what exactly had happened to the card at the hotel. My husband began explaining that the bank had frozen it without warning. I corrected him. I had frozen the additional cards after discovering that they were attached to my account. He looked at me sharply, but I continued. I wanted her to understand that the decline wasn’t a technical mistake and that nobody had stolen the cards. I had stopped further spending deliberately.
She frowned. “I thought something had happened with the bank,” she said. Her voice contained more confusion than accusation. My husband told her he had already explained the problem in the car. She answered that he had only said the cards were blocked. I watched them carefully. Their disagreement was small, but it revealed something significant. He had been speaking on behalf of everyone involved. Until now, I had allowed him to make me believe they all shared the same understanding.
His sister asked whether I had actually canceled their cards. I told her they were frozen, not permanently closed, and that I would not restore access. She pressed her lips together. “That explains why the hotel wouldn’t accept the payment,” she said. My husband interrupted to tell her that the hotel had overreacted. I asked how a hotel was supposed to react when an attempted payment was declined. He said that wasn’t important. I replied that it seemed important enough to end the vacation.
My father lifted a crate into the truck while we spoke. The rough scrape of wood against metal briefly interrupted the conversation. I was grateful for the sound. It reminded me that the entire world had not stopped because my husband was angry. There were ordinary tasks waiting, people who had been working since morning, and children inside the house who expected us to behave like responsible adults. I had no desire to shout. I wanted answers that could survive being spoken at a normal volume.
I asked my mother-in-law whether she had brought the card with her. She opened her handbag and searched through a leather wallet. After a moment, she withdrew it and held it between two fingers. “Here,” she said. “I certainly don’t want it causing any more trouble.” I took it, feeling the smooth plastic against my roughened hands. Her name appeared on the front, just as I had seen it listed in the account portal. But the card number was tied to credit that belonged to me.
I held it where everyone could see. “This is an additional card on an account I opened,” I explained. “The primary account is in my name, and the debt is my responsibility.” My mother-in-law looked genuinely surprised. She leaned closer, as though the front of the card might confirm something she had overlooked. My husband quickly said that all the household finances were interconnected anyway. I asked him which part of that statement gave him the right to arrange borrowing without telling me.
He rubbed his forehead. “You’re using the wrong words,” he said. “Nobody borrowed anything from you. It was a convenient way to organize travel spending.” I asked why travel spending needed to be organized through an account I didn’t know his family was using. He answered that I already had enough expenses to worry about and that he had been taking care of everything. I looked at the card. In his version of events, keeping me uninformed had somehow become a favor.
His mother lowered herself onto the bench. “I don’t understand,” she said. “You told me this was your travel account.” She was speaking to him, not to me. He turned toward her and said he had handled the payments, which was essentially the same thing. She shook her head. “No, it isn’t.” He looked irritated by the distinction. I felt something shift. For the first time since discovering the statements, someone other than me was asking him to explain what his words had actually meant.
I took the folded sheet from my pocket. Before he arrived, I had printed a summary from the account records I saved. The sheet listed the eleven-month period, the additional cards, and the charges I could associate with their use. It did not include every detail from my account, and I had no intention of handing over sensitive information unnecessarily. But the total was unmistakable. I told them the additional spending amounted to $18,731 before the hotel charge that had been declined that morning.
His sister stared at me. “That can’t be right,” she said. I turned the page so she could see the total. My mother-in-law asked whether it included the vacation they had just attempted. I explained that the failed $4,800 payment hadn’t been added. She looked at her son again. He shifted his weight and told everyone the number sounded worse without the proper context. I asked what context could alter the fact that the charges had occurred without my knowledge.
He began listing ordinary explanations. Some spending had been for holidays, some for family celebrations, some for restaurants during visits, and some for travel that he considered important. I listened without interrupting. There was no point arguing over whether a particular dinner or hotel room had been enjoyable. The question was whether I had agreed to finance it. When he finished, I asked when he had first decided to use my account this way. He stared at the paper rather than answering.
His mother spoke slowly. “You told me not to worry about the cost.” My husband nodded, visibly relieved to hear something he could agree with. “Exactly. I told you I’d handle it.” She shook her head. “You said you were paying.” He replied that he had been planning to pay the account. She asked whether that meant he hadn’t paid it. The silence that followed was longer than any we had experienced at the hotel call. I watched his jaw tighten.
At last, he said he had been making payments toward our finances generally. I asked for a specific amount. He told me I knew our income and bills, and that there was no reason to separate every transaction into individual categories. I pointed toward the paper. The charges on those additional cards were already separated into categories because the card issuer recorded them. If he had been managing repayment, he should be able to show the corresponding payments. He became angry again.
“Are you going to stand here auditing me?” he asked. His use of the word made me almost smile, though there was nothing amusing about the situation. For months, he had inspected small purchases as though every household receipt represented a possible failure of character. Now a substantial sum had appeared on my account, and he treated basic questions as a personal attack. “I’m asking you to explain a balance you helped create,” I said. “You can call that whatever you like.”
His sister took the paper from the bench and studied it. She pointed to several charges and said she remembered making those purchases during trips. Others she couldn’t identify immediately. I told her she could compare the statements later if she needed to understand the details. She asked whether I was saying they had spent almost nineteen thousand dollars between them. I said those were the charges associated with the additional cards. I wasn’t going to assign individual responsibility until I had verified the transactions.
My husband seized on that distinction. “So you don’t even know who spent what,” he said. I agreed that I still needed to examine the individual charges carefully. He looked triumphant for a moment, as though identifying an unanswered question invalidated all the answered ones. I reminded him that the cards were still linked to my account and that I had never approved the arrangement. Whether his mother paid for a dinner or his sister purchased something during a trip did not change that fundamental fact.
My mother-in-law looked at him with an expression I had rarely seen. She usually defended him automatically, sometimes before understanding what anyone was accusing him of doing. She had once told me that he carried too much responsibility and that I ought to be more appreciative of the pressure he lived under. Today, however, she seemed to be discovering that the responsibility he claimed might include decisions he had concealed from the person who would ultimately bear their cost.
“I need you to tell me something,” she said. He turned toward her, evidently expecting sympathy. “When you handed me that card, you told me I could use it for our trips because you had set money aside. Did you know it was connected to her account?” He gave a vague answer about managing household money together. She asked again, this time more firmly. He said he knew how the account worked. She looked away from him and stared at the field beyond the shed.
I remembered the months when he had asked me to reduce our grocery budget. I remembered putting back items our children liked because I couldn’t justify their price under the limits he had established. It would have been easy to recite every one of those incidents in front of his mother. I wanted her to understand the contrast, but I didn’t want the conversation to become a contest over whose sacrifices sounded more impressive. Instead, I asked him why he had demanded so much restraint from me while allowing the additional spending to continue.
He said the two issues weren’t comparable. His mother’s travel, he argued, was occasional and important. The household budget required daily attention. I asked what made a restaurant bill more important than shoes for a child. He told me not to use the children against him. I felt a sharp surge of anger, then forced myself to speak slowly. I hadn’t involved the children in the financial arrangement. He had affected their lives by insisting money was too tight for ordinary necessities while keeping these charges hidden.
My father quietly approached and asked whether anyone wanted water. My mother-in-law accepted a glass. My husband declined with a dismissive movement of his hand. His sister took the opportunity to ask if we could continue inside somewhere cooler. I explained that the children were in the house with my mother and that I preferred to keep the disagreement away from them. She glanced toward the screen door, then nodded. For a moment, I saw how uncomfortable she was with being involved in something she had expected to remain a simple vacation.
My husband made another attempt to move the conversation. He suggested we drive home together and discuss the balance after the children were asleep. I told him we could have a private conversation later about our marriage, but the people who held the additional cards needed to know whose account they were using. He said there was no reason to upset his mother. She answered before I could. “I’m already upset,” she said. “And I’d rather understand why.”
He looked at her in disbelief. I realized he had expected their presence to strengthen his position. Perhaps he imagined they would tell me I was overreacting or that the embarrassment at the hotel was unforgivable. Instead, the more they learned, the less certain they became about his version of events. His mother wasn’t defending me out of loyalty. She was asking questions because the explanation she had been given no longer matched the evidence in front of her.
His sister folded the statement carefully and laid it on the bench. “I knew you wanted us to use the cards,” she told him. “But I thought you’d already arranged the payments.” He said that was precisely what he had done. She asked whether the balance was currently owed. I answered that charges were reflected on my account and that we needed to reconcile the statements and payments before determining the exact remaining amount. Her expression changed. She had been treating the plastic in her wallet as a convenience, not as access to somebody else’s credit.
A breeze came across the field, lifting the corners of the paper. I placed my hand over it and asked a question I had avoided until then. “Did either of you ever hear him say the account was mine?” My mother-in-law answered immediately. “No.” His sister hesitated. My husband turned toward her so quickly that I could see the warning in his face. He said she didn’t need to get involved in a marital dispute.
His mother set down her glass with a hard, deliberate movement. “You’ve involved all of us already,” she said. He opened his mouth, but she raised one hand. “I want to hear what she has to say.” The younger woman looked between her brother and me. I didn’t urge her to answer quickly. Whatever she knew, I wanted her own words, not another explanation shaped by him.
She finally said she had never seen the primary account statement. She had been told the card was provided for family trips and that her brother was looking after the bills. She admitted she had not asked many questions because she trusted him. My husband immediately said that proved everyone had understood the arrangement. His mother looked at him with visible disbelief. “No,” she said. “It proves we trusted the person who handed us the cards.”
He drew a breath and tried to respond, but she wasn’t finished. She asked why he had allowed her to believe he was covering the expenses when he knew the account belonged to his wife. He stared at the ground. His mother stood up slowly, her face no longer confused. She looked directly at him and asked the question that changed the entire afternoon: “When you gave us those cards, were you ever planning to tell your wife what you had done?”
END PART 6
PART 7 TITLE: The Questions My Husband Had Avoided for Eleven Months Finally Came From the Two People He Expected to Defend Him
My mother-in-law’s question hung between us while a truck passed on the county road beyond the field. My husband watched it disappear as though the interruption might give him time to find an acceptable answer. He had been quick to explain the hotel’s inconvenience, quick to condemn my decision, and quick to describe his intentions. Now that his mother had asked whether he ever planned to tell me about the cards, he seemed unable to produce a single direct sentence.
“I wasn’t hiding some enormous secret,” he said eventually. “I just didn’t think it needed to become a discussion every time someone booked a room or paid for dinner.” His mother continued looking at him. I asked whether that meant he had consciously decided not to tell me. He exhaled and said I was determined to interpret everything in the worst possible way. I did not raise my voice. “I’m asking about a decision you made,” I said. “Not about my interpretation of it.”
He glanced toward his sister, perhaps hoping she would interrupt with another complaint about the shortened vacation. She remained beside the bench, her hands resting on the straps of her travel bag. Her silence appeared to bother him. He told us the account had been available for years and that his use of it hadn’t created a problem until I started digging through old statements. I reminded him that an undiscovered problem didn’t become acceptable simply because nobody had noticed it yet.
My mother-in-law asked whether the cards had been requested recently or long before. I answered that the transactions extended across eleven months and that I still intended to confirm the original request dates with the card issuer. My husband said he couldn’t remember precisely when he had arranged everything. His mother frowned. “You remember booking every hotel,” she said. “Surely you remember deciding whose account would pay for them.” He looked away, apparently realizing that she was not going to help him dismiss the subject.
I unfolded the statement summary again. The paper was creased from being handled, and one corner had picked up a faint brown mark from the workbench. I laid it flat so the three of them could see. I explained that the individual charges mattered because they showed a pattern over time. A single mistaken purchase might have been corrected with a conversation and reimbursement. Repeated use of two additional cards over eleven months suggested an arrangement that had been deliberately allowed to continue.
My husband’s sister bent over the page. She recognized several hotel and restaurant names immediately. At one entry, she stopped and said she remembered a weekend trip with their mother. At another, she mentioned a family meal that had seemed unusually expensive at the time. I let her speak without interrupting. I wasn’t asking her to confess to wrongdoing simply because she had used a card someone else supplied. I wanted everyone to understand what the records established and what questions remained unanswered.
She straightened and looked at her brother. “When I asked if I needed to cover my part, you said everything was taken care of.” He nodded impatiently. “Because I was taking care of it.” She shook her head. “But you never said she was responsible for the account.” He insisted that spouses shared finances and therefore the distinction was meaningless. I told him our marriage did not eliminate my right to know who was authorized to use my personal credit.
He turned toward me. “Are you seriously going to make me ask permission every time I help my mother?” I answered that helping his mother was not the same thing as extending my credit to other people. He could choose what to do with money he controlled and obligations he had agreed to assume. If he wanted me to participate, he needed to ask. He said I was treating his family like strangers. I replied that knowing them made honest communication more important, not less.
My mother-in-law held out her hand for the statement. I gave it to her, and she read several entries slowly, adjusting her glasses. She asked whether the charges included meals she had believed her son was paying for. I confirmed the ones I could identify from the records. She pressed her lips together and asked if I had been aware of any of those expenses when they occurred. I shook my head. The only way I had learned of them was by reviewing the account myself.
For a few moments, she said nothing. I could almost see her recalling the occasions when my husband had insisted on paying for something and waved away any offer to contribute. She had often praised him for his generosity. At family gatherings, she told people how fortunate she was to have a son who took care of everyone. I had heard those compliments many times while wondering why he seemed so anxious about the smallest expenses at home. I had never connected the two things.
“I need to understand something,” she said. “When you told me I didn’t have to worry about paying you back, did you already know this account was in her name?” My husband answered that he knew where all the money came from. She asked again, more firmly. He admitted that he knew it was my account but insisted he had never intended for me to be left with the expense permanently. She asked what arrangement he had made to prevent that. He could not describe one.
He tried to change the subject to my decision to freeze the cards. He said I had known the family was traveling and could have waited until they returned. He described the confusion at the hotel, the embarrassment of having a payment declined, and the inconvenience of arranging another method of payment. He spoke as though the timing of my discovery was the central offense. I listened until he stopped. Then I asked whether there would ever have been a convenient time for me to learn the truth.
He didn’t answer. His mother did. “There wouldn’t have been,” she said quietly. I turned toward her. She was still holding the statement, but she wasn’t looking at it anymore. “If she hadn’t found those cards herself, you wouldn’t have brought them up,” she told him. He objected that nobody could know what he would have done. She replied that eleven months had already passed. That was enough time for a conversation he claimed he intended to have.
Her words mattered because they were not based on loyalty to either of us. She wasn’t trying to punish her son or protect me from every unpleasant consequence. She was identifying the same fact the account history revealed. There had been repeated opportunities to disclose the arrangement, and he had allowed every one of them to pass. I had been asked to trust his financial judgment without being given the information necessary to evaluate it.
My sister-in-law looked toward the kitchen. “Are the kids inside?” she asked. I told her they were helping my mother prepare supper. She nodded, then said she had heard my husband talk about our household budget before. He had mentioned that we were trying to spend less and that things were getting expensive. She hadn’t realized the restrictions were affecting ordinary purchases. I asked whether she had known he was questioning our grocery spending while the additional cards were being used. She said she hadn’t.
My husband became defensive. He said every family needed priorities and that spending on travel didn’t mean he was careless about household expenses. I asked him to explain how he determined those priorities. He could speak at length about the importance of his mother’s comfort, the value of family holidays, and the need to enjoy life occasionally. Yet when I mentioned our children’s needs, he returned to the language of discipline and patience. The contradiction was becoming too clear for anyone standing there to ignore.
I remembered a particular Saturday when our daughter had been disappointed because I told her we needed to delay buying shoes. The old pair hadn’t become unusable yet, but the soles were beginning to loosen. She hadn’t complained or demanded anything expensive. She simply asked whether we could look again the following week. I had said yes and felt guilty afterward for making such a small necessity sound like an extravagance. At that same time, charges were continuing on the additional cards.
My mother-in-law listened as I explained the incident. Her expression tightened. She looked at her son and asked whether he had known the children needed things while the travel spending continued. He said I was exaggerating the circumstances and that the children had never been deprived of essentials. I told him I wasn’t accusing him of leaving them without food or shelter. I was saying he had imposed restrictions on ordinary family expenses while concealing spending he had decided deserved a different standard.
My father came toward us carrying a small cooler. He set it beside the bench, offered another round of water, and asked whether we needed anything else. I thanked him and said we were managing. He glanced at my husband without comment. I knew he was concerned, but I also knew he understood that the conversation belonged to the people directly involved. He returned to his work, leaving us with the cooling shade and the account statement lying between us.
My husband watched him go. “Your father must think I’m some kind of criminal,” he muttered. I told him my father hadn’t accused him of anything. “Then why is he standing around listening?” I pointed out that this was my parents’ property and that we were discussing the matter in their farmyard because he had chosen to come there. He had brought his mother and sister with him. Nobody had been summoned to a courtroom or exposed to strangers. We were simply refusing to pretend that the disagreement involved only his pride.
He said I could have avoided the entire situation by unlocking the card and discussing the balance later. I asked what assurance I would have had that another discussion would be any more productive than the ones we were having now. He replied that I should have trusted him. The words landed heavily. Trust was precisely what the eleven months of statements had damaged. He was asking me to continue acting as though his judgment were unquestionable after discovering that he had hidden information essential to my own financial security.
His mother folded the summary and placed it beside my hand. She said she wanted to know whether the card account had been presented to the younger sister the same way it had been presented to her. My sister-in-law answered that she had been told it was for family travel and that her brother had taken care of the expenses. She said she had not understood that I might be unaware of the charges. She paused, then added that she should have asked more questions before continuing to use it.
I appreciated the distinction she was making. She wasn’t claiming that a card became harmless simply because someone else provided it. Nor was she pretending the charges had disappeared. She was acknowledging that she had accepted an explanation without understanding its consequences. I told her that the transactions still needed to be reviewed, but that I did not want to accuse anyone of knowingly taking advantage of me without first establishing what each person had been told.
My husband seemed irritated by the care I was taking. He said that if I believed his mother and sister hadn’t understood, I should stop acting as though something terrible had happened. I asked whether he believed the arrangement was acceptable simply because he had kept several people uninformed. He looked at me without speaking. His position depended on each of us accepting a different explanation. Now that we were comparing them, there was no version that made everyone equally responsible for the concealment.
His mother asked him to stop interrupting. She said she was embarrassed to learn that purchases she believed her son had funded were connected to my credit. She hadn’t agreed to impose those expenses on me, and she would not accept being used as an excuse for hiding them. He told her she was making him sound dishonest. She looked directly at him. “You gave me an explanation that left out the person who owned the account,” she said. “What would you call that?”
He answered that he had believed he could manage the payments. I asked what had changed between that belief and the present situation. He said there had been other expenses and that money had become tighter than expected. It was the first time he had come close to admitting that his arrangement wasn’t supported by a definite repayment plan. I felt the temptation to interrogate him further, but I resisted. An incomplete admission still needed to be tested against the actual account records.
I asked him whether he would provide a complete accounting of the charges and any payments made toward them. He said I already had the statements. I explained that the statements showed card activity, not everything he had promised his mother and sister or how he intended to make me whole. He asked whether I was going to make him sign something. I told him we weren’t discussing paperwork yet. We were discussing the truth, and I needed more than assurances that everything would eventually work out.
My sister-in-law quietly removed her card from her wallet. She held it for a moment, turning it over in her fingers. “I don’t want to use this anymore,” she said. My husband told her she was overreacting. She looked at him with disappointment rather than anger. “I used it because you said you were paying,” she answered. “Now I don’t even know what that meant.” She placed the card on the bench beside the statement.
His mother looked at the card and then reached for the one she had already returned to me. I showed her where I had placed it. She picked it up and examined it carefully, as though seeing the object for the first time. I thought about how little physical evidence was required to create such a large problem. Two pieces of plastic, eleven months of routine transactions, and a husband who believed he could keep every explanation separate until nobody had enough information to question him.
He made one final appeal to his mother. He said she had always taught him to look after family and that he was being criticized for doing exactly that. She held the card between her fingers and shook her head. “I taught you to help people with what you can honestly offer,” she said. “I didn’t teach you to promise someone else’s resources without asking them.” He stared at her, looking more wounded by her refusal to defend him than by anything I had said.
The sounds of the farm began to change as the afternoon moved toward evening. My mother appeared briefly at the kitchen door and called that the children were washing their hands. My father backed his pickup toward the next stack of crates. The harvest still needed attention, and I was conscious of how long we had been standing there. Yet I also knew we were finally discussing facts that had been avoided for nearly a year. I wasn’t willing to stop simply because the conversation had become uncomfortable.
I looked at my husband and told him the cards would remain blocked. I would not approve another charge or agree to a repayment arrangement based only on promises. He asked what I expected him to do instead. I said he needed to account for the money, explain how the additional users had been added, and stop presenting his decisions as obligations I was required to accept. He looked toward his mother, but she gave him no help.
Then she asked him something neither of us had mentioned directly. “When you put our names on her account, did you ever ask her?” He began with another explanation about how married people usually managed finances. She interrupted. “That isn’t what I asked.” He stared at the card in her hand. She repeated the question, slowly enough that there was no possibility of misunderstanding. This time, after a long silence, he admitted that he had not.
END PART 7
PART 8 TITLE: When His Mother Refused to Defend the Secret Credit Cards, My Husband Discovered That an Apology Would Not Settle the Debt
My husband had finally admitted that he never asked me before arranging the additional cards. The words had come reluctantly, almost as though he hoped their significance would disappear if he spoke them softly enough. His mother stood opposite him with the card in her hand. His sister remained beside the bench, watching the ground. For several seconds, nobody moved. The silence was not comfortable, but I preferred it to another explanation designed to make the facts seem less serious.
“Then why did you do it?” his mother asked. He rubbed both hands over his face before answering. He said it had been convenient, that he knew the account existed, and that he believed he could keep the payments under control. He reminded her that she had wanted to travel more and that his sister had been looking forward to spending time with her. I listened to him present good intentions as though they could substitute for permission. He had decided what everyone should receive, then quietly assigned the financial obligation to me.
His mother did not look impressed. “I never asked you to use your wife’s credit,” she said. He replied that she had never asked how the trips were funded either. She accepted that point without hesitation. She said she should have been more careful about understanding the arrangement, especially when she continued to use the card for months. But she would not accept his attempt to turn her trust into permission to mislead me. Her willingness to acknowledge her own part made his excuses seem even thinner.
I had expected this confrontation to produce anger from every direction. I had imagined his mother accusing me of humiliating her at the hotel, his sister defending the spending as normal, and my husband demanding that I apologize for ruining their vacation. Instead, the discussion had become something he seemed completely unprepared to handle. People were asking him direct questions and refusing to let him answer a different one. The change was so unfamiliar that I almost felt uneasy standing in the middle of it.
My sister-in-law pulled the remaining card from the bench and offered it to me. I accepted it without ceremony. There was no satisfaction in holding something that had represented so much concealed spending. The plastic was light, barely noticeable between my fingers. Yet the account behind it contained nearly a year’s worth of decisions that had affected our household. I placed both additional cards inside the small zippered pocket of my bag, where they would remain until I had confirmed with the issuer that access was permanently removed.
My husband watched the movement. “You don’t have to treat us like we’re dangerous,” he said. I looked at him and asked what he thought I should do with cards that had been used without my authorization. He suggested putting them away until we settled the disagreement. I told him that was exactly what I was doing, except that I would also make sure they could no longer be used. He seemed offended by the practical distinction. To him, every safeguard looked like an accusation.
His mother asked whether he had ever shown me the additional-user information or discussed the transactions at home. He told her I could have reviewed the account at any time. I answered that I had reviewed it, which was why we were standing there. His argument relied on the idea that my ability to discover something excused his failure to disclose it. I asked whether he would have considered it acceptable if I had quietly added my relatives to an account in his name and allowed them to spend thousands of dollars.
He said that wasn’t the same situation. I asked what made it different. He reminded me that his mother was older and that he felt responsible for making sure she enjoyed herself. I told him I understood the desire to help a parent. We were standing on my parents’ farm because I had chosen to help them with their harvest. The difference was that I had offered my time and labor openly. Nobody had arranged a secret account or claimed authority over resources that belonged to someone else.
My mother-in-law sat again, looking exhausted. She said she had never considered herself extravagant, but the statements made her question how much she had allowed herself to spend because she believed her son was taking care of everything. She asked for copies of the charges associated with her card so she could review them. I told her I would provide a clear transaction list once I had checked the details. She nodded and said she wanted to understand what she had purchased, not merely what her son had told her about it.
His sister made a similar request. She said there were charges she recognized and others she would need to check against travel dates and receipts. I appreciated that neither woman was asking me to accept a vague assurance that everything was harmless. They wanted to know what had happened. Whether they eventually contributed to repayment would require another conversation, but at least the first step was possible. Everyone could examine the same records instead of relying on separate stories.
My husband remained unconvinced. “Now you’re all going to start calculating who owes what?” he asked. His mother looked at him. “Someone has to.” He shook his head and said families shouldn’t operate like businesses. She answered that family relationships did not make financial obligations imaginary. The exchange was brief, but it revealed how little support remained for the explanation he had expected everyone to accept.
I took a fresh sheet of paper from the folder and explained what I intended to verify. The card issuer could confirm when the additional users had been added and what procedures had been followed. The statements would identify transactions by card number, while receipts might clarify the purpose of particular purchases. Payments already made would need to be matched against the account activity. I was not claiming that every dollar of the $18,731 remained outstanding. I wanted to know precisely what had been charged, what had been repaid, and what liability remained.
That distinction mattered to me. I knew how easily anger could lead a person to make accusations that went beyond the evidence. I had already spent too much time being told I was emotional or unreasonable. I would not strengthen that description by making careless claims. The records established an undisclosed arrangement and a substantial amount of spending. The rest needed to be examined honestly, even if the findings were less dramatic than my worst suspicions.
My husband asked why I was so determined to involve the card company. I said I needed to ensure no further spending could occur without my permission. He told me the cards had already been returned, making additional steps unnecessary. I pointed out that the physical cards were only one part of the arrangement. Saved payment details and account permissions could remain active unless they were properly removed. I wanted confirmation, not assumptions. He didn’t like the answer, but he couldn’t offer a practical reason for leaving the access in place.
He shifted his attention toward the hotel. He said the staff had treated his mother as though she were trying to use an invalid card and that the experience had been humiliating. His mother corrected him. The staff had simply explained that the payment could not be approved and requested another form of payment. They had not accused her of anything. She had been upset because she believed the problem was a mistake and because her son appeared unable to fix it. Her embarrassment had grown when she learned the actual reason.
He looked startled by her willingness to describe the incident differently. I wondered whether he had told himself the same story so often during the drive back that he believed it completely. In his version, I had created a crisis by blocking an ordinary family payment. In hers, the payment had failed because the person responsible for the account had discovered an arrangement she never approved. The difference was not a matter of tone. It changed who had the right to decide what happened next.
My father called from the truck, asking whether I could help him secure the final load. I told him I would be there shortly. My husband turned toward him with visible irritation, as though ordinary farm work were an interruption to a matter that should command everyone’s full attention. I remembered the remark he had made before leaving for vacation, when he treated the harvest as a useful hardship for me and the children. Now the work he had dismissed seemed like an excuse to avoid his demands, and he resented it for that reason.
I asked whether he wanted to help my father finish loading. He looked at his clean shoes and said we were in the middle of something important. I agreed that we were. I also told him the conversation had been going on long enough for everyone to understand the central facts. There would be more to discuss after the records were reviewed. Standing in the yard and repeating the same arguments would not produce a repayment plan or restore trust. I had work to finish, and I intended to finish it.
He stared at me. “So that’s it? You’re just going back to picking corn?” I told him the harvest was nearly complete and that I had promised to help. He asked whether I expected him to stand there while I ignored him. I reminded him that he had spent the morning telling me how important family obligations were. My parents needed help, and I was honoring a commitment I had made openly. If he wanted to continue the financial conversation, he could begin by preparing the information I had requested.
His mother looked at the remaining crates. She asked my father whether there was anything useful she could do while we finished. He seemed surprised but directed her toward a table where my mother had left a small pile of corn to sort. My sister-in-law offered to help as well. Neither looked particularly prepared for farm work, and I suspected the heat and travel had already exhausted them. Still, their willingness to do something ordinary after such an uncomfortable conversation seemed more genuine than any elaborate statement of regret.
My husband watched them move toward the table. “You don’t have to do that,” he told his mother. She answered that she was perfectly capable of helping for a few minutes. He said she had been traveling all day. She reminded him that I had been working in the field while he was away and that my parents had been working longer still. Her words weren’t intended to humiliate him. She was simply refusing the special treatment he had used to justify the entire vacation.
I helped my father lift the next crate into the pickup. The work required both hands, so I stopped looking at my phone and stopped trying to anticipate what my husband might say. My arms were tired, but the repetitive motions helped steady me. Beside the packing shed, his mother and sister began sorting corn under my mother’s guidance. My husband remained near the car, his shoulders rigid, clearly uncertain whether joining the work would look like surrender.
After several minutes, he came over and lifted one of the smaller crates. He didn’t speak, and I didn’t thank him for doing what everyone else had been doing since morning. We worked side by side briefly, the distance between us measured less by the space separating our shoulders than by everything that had been said. It occurred to me that he might be waiting for the argument to dissolve through ordinary activity. That had happened before. We would stop speaking about an issue, resume familiar routines, and eventually behave as though nothing remained unresolved.
I wasn’t going to let that happen with the account. When we set the crate down, I told him I needed him to provide any records he had concerning the additional cards and the payments he claimed to have arranged. He said he would look through his information when we got home. I asked him to put whatever he found in writing so we could compare it with the statements. He looked irritated, but he agreed. I told him I would be contacting the issuer independently and reviewing our other accounts as well.
“Do you really trust me that little?” he asked. I considered several possible answers. The easiest would have been to reassure him that of course I trusted him and that I simply wanted to clear up a misunderstanding. But I could not say it truthfully. “Right now,” I answered, “I don’t know what you’ve told me accurately about our finances. That’s what I need to find out.” He turned away. For once, I allowed the discomfort of my answer to remain.
His mother approached us carrying an empty basket. She said she had been thinking about the hotel and the charges. She wanted me to know that she would not use another card without understanding precisely who was responsible for it. She also wanted to review her past purchases and discuss how she might address her share. I thanked her for saying so but told her we should first establish the correct figures. I didn’t want promises made in embarrassment to become another source of confusion.
His sister came over and said she agreed. She wasn’t comfortable discovering that the conveniences she had accepted might have created expenses for someone who had never approved them. She said her brother had always seemed certain he could handle the costs, and she hadn’t questioned him. I told her I understood that distinction, but I also explained that going forward I expected everyone to ask before assuming access to another person’s financial resources. She nodded without arguing.
My husband listened with increasing frustration. Finally, he said that we were all behaving as though he’d set out to hurt me. I told him I was not trying to read his mind. I could not prove what he intended eleven months ago or what he might have done if I never discovered the cards. What I knew was what had happened. He arranged access to my account, allowed substantial spending, insisted our household cut expenses, and did not tell me about the arrangement. Those facts were enough to require meaningful changes.
He said he understood and wanted to put the matter behind us. I looked at him carefully. It was the first time he had expressed any willingness to move beyond defending the vacation. But wanting something to be over was not the same as taking responsibility for it. I asked what he understood. He answered that I was angry about the spending. I corrected him gently but firmly. The spending mattered. The concealment mattered more. I needed him to understand why those were separate problems.
His mother stepped closer before he could respond. She held out her empty hand toward the pocket where I had placed the returned cards. “Those stay with you,” she said. My husband immediately objected that there was no reason to make a permanent decision. She looked at him with the same calm firmness she had shown earlier. “There is no reason for your wife to reopen the cards just because this has become inconvenient for us.”
He asked whether she was seriously taking my side. His mother shook her head. “I’m not choosing between you,” she said. “I’m recognizing whose permission was missing.” He looked genuinely shocked. I realized that he had counted on his mother to protect him from the consequences of his choices, just as he had counted on me to absorb their cost. She was refusing to play that role. Whatever disagreements she and I might have had in the past, we were finally discussing the same reality.
My mother called from the kitchen that supper would be ready soon. Through the screen door, I could hear the children talking and the scrape of chairs across the floor. The evening light had softened over the field, and the last crates were secured on the truck. My father checked the straps once more, satisfied that the load was ready. The ordinary work of the day was nearly done. The larger problem was not. Eighteen thousand, seven hundred thirty-one dollars in recorded charges still required examination, and a marriage built partly on unquestioned trust now faced questions that could not be answered with affection alone.
My husband asked whether we could at least agree that the discussion was finished for the day. I told him we could stop arguing, but we could not pretend the issue had been resolved. He would need to produce the information he promised, and I would need to complete my own review. We would then discuss the remaining financial responsibility and what changes were necessary. I wasn’t going to make decisions about forgiveness, repayment, or the future of our marriage while he was still struggling to acknowledge the basic facts.
He nodded reluctantly and looked toward the house. His mother and sister moved away to wash their hands. My father walked past us carrying an empty basket, and I followed him toward the packing table. There was one small pile of corn remaining, several ears that needed to be sorted before supper. I picked one up and began removing the loose silk. Behind me, my husband stood quietly for a moment, then asked, “What am I supposed to do now?”
I looked back at him. Eleven months earlier, I would have answered immediately. I would have found a way to reassure him, helped him organize the payments, and accepted some portion of responsibility simply to restore peace. Today, the familiar impulse was still there, but I no longer mistook it for an obligation. “Start with the records,” I said. “Show me what happened, what you’ve paid, and what you still owe. Then we can discuss what responsibility looks like.”
He seemed to expect something more forgiving, but I turned back to the basket. The account was protected for now. His mother and sister had returned the cards and acknowledged what they had not understood. My husband had finally admitted that he never sought my permission. None of those developments erased the past eleven months, and I could not yet say what they would mean for our marriage. What had changed was that I would no longer accept promises as substitutes for answers.
As I placed the last ears of corn into the basket, I heard my father closing the pickup’s tailgate. My children called from the kitchen, asking whether I was coming inside. I told them I would be there in a minute. My husband remained beside the table, watching me, but I did not hurry to comfort him or soften the boundaries I had established. The next decisions were his to make, and this time he would have to make them with the truth visible to everyone involved.
END PART 8
PART 9 TITLE: After the Last Crate Was Loaded, My Husband Had to Explain Why He Protected Everyone Except the Person Paying
The final basket was still in my hands when my husband stepped away from the packing table. He had asked what he should do, and I had given him an answer that required something I no longer knew he was capable of offering: a complete account of his decisions. He stood near the shed for several seconds, looking as though he expected me to call him back and make the conversation easier. I did not. I carried the basket toward the kitchen, where my children were waiting for supper.
Inside, the farmhouse smelled of butter, boiled corn, and the bread my mother had warmed in the oven. Our daughter was arranging forks beside the plates, while our son tried to convince his grandmother that he had carried more baskets than anyone else. Their argument was cheerful and entirely serious. I washed my hands at the sink and watched brown water disappear down the drain. The skin across my knuckles was dry and rough. I had worked hard all day, but the exhaustion in my body was simpler than the weight of the conversation outside.
My husband entered a few minutes later. His mother followed him, carrying her handbag, and his sister came behind them. The three had left for a luxury vacation that morning. Now they stood awkwardly in my parents’ kitchen, unsure whether they were guests, participants in an argument, or both. My mother greeted them politely and offered supper. My mother-in-law accepted after a moment’s hesitation. My husband said he wasn’t hungry, then sat down when our son pulled out a chair and asked why Dad looked so tired.
Nobody explained the argument to the children. My father asked about school, my mother passed around the corn, and I listened while our daughter described the ear she had found with an unusually crooked row of kernels. My husband answered when spoken to, but his attention kept returning to me. He seemed surprised that I could continue eating and talking after refusing him something he considered so important. Perhaps he had expected the rest of the evening to revolve around his anger. Instead, the children needed supper, the dishes needed washing, and my parents had a delivery to prepare.
During the meal, my mother-in-law thanked my parents for feeding everyone without warning. My mother told her there was plenty. My husband made a small comment about how inexpensive the meal must have been, given that most of it came from the farm. He spoke lightly, but I noticed my father’s expression change. My father set down his fork and explained that growing food required equipment, fuel, repairs, water, and many hours of labor. The fact that the family shared the harvest did not make it free. My husband looked down at his plate.
I had spent eleven months listening to him describe financial responsibility as though he alone understood its demands. Yet my parents had been practicing a much less theatrical version of it for decades. They planned, repaired, saved, and asked for help when they needed it. They knew what a dollar cost because they understood the work behind it. My father had not intended to embarrass anyone with his remark. He had simply refused to let the value of their work disappear because the result happened to be sitting on the table.
After supper, his mother offered to help clear the dishes. I watched her standing beside my mother at the sink, carefully stacking plates while the two women discussed the weather and the next day’s deliveries. They had never been especially close. Their conversations usually remained polite and superficial, conducted around birthdays and holidays. Tonight, however, there was a new awkwardness between them. My mother knew about the credit cards, and his mother knew she knew. Neither woman seemed interested in pretending the discovery had not happened, but they were also unwilling to turn the children’s supper into another confrontation.
My husband approached while I was drying a serving bowl. “Can we go home?” he asked quietly. I told him I would take the children once they finished helping their grandfather. He asked whether we could drive together. I reminded him that I had arrived in my own vehicle and that his mother and sister had traveled with him. He suggested leaving them there temporarily. I looked at him for a moment. Even now, he was searching for a way to separate the people involved and return to a conversation in which he could control the explanation.
“Take your mother and sister home,” I said. “I’ll bring the children back after we finish here.” He lowered his voice further. He wanted us to talk without an audience. I agreed that a private conversation was necessary, but I told him it would not replace the questions his mother and sister were entitled to ask about their cards. His jaw tightened. He asked whether I intended to punish him indefinitely. I said I hadn’t established any punishment. I had stopped unauthorized access to my credit and asked him to explain what he had done.
He watched me put the bowl away. “You could have warned me before the hotel,” he said. I turned toward him, astonished that he was returning to the same complaint. He explained that a short message before the trip might have allowed him to arrange another payment method. I reminded him that I discovered the cards the previous evening, froze them, and waited to understand what had happened. He was suggesting that my first responsibility after discovering the arrangement should have been to protect him from its consequences.
I asked whether he had considered warning me before giving anyone access to my account. He didn’t answer immediately. Then he said the situation had seemed harmless at the beginning. I asked what the beginning looked like. He described wanting to make travel easier for his mother and sister, avoiding repeated discussions about expenses, and using an account that already had available credit. He spoke of convenience repeatedly. It struck me that convenience had become his explanation for decisions that were difficult for everyone else to undo.
“At what point did you realize I didn’t know?” I asked. He frowned. “What do you mean?” I clarified that I wanted to know whether there had been a moment, after the first few transactions, when he recognized I remained unaware of the additional cards. He said of course he knew I hadn’t been following every purchase. I told him that wasn’t what I had asked. His eyes moved toward the kitchen doorway, where the children were laughing with their grandfather. He said we should discuss it later.
We left the farmhouse after sunset. My mother packed corn into a paper bag and handed it to our daughter, who insisted on carrying it herself. My father checked that the back of my vehicle was clear before helping our son fasten his seat belt. He said nothing about my marriage. Before I got into the driver’s seat, however, he rested a hand briefly against the open door and told me I could come back whenever I needed to. His voice was practical, without drama. I thanked him and drove away.
The children fell asleep before we reached the main road. I watched their faces in the rearview mirror whenever the headlights from another vehicle passed over them. Our daughter still had a faint line of dirt across her forehead, and our son’s hands were curled loosely around the straps of his seat belt. They had spent the day working, playing, and learning something about their grandparents’ lives. I wanted them to remember the cornfields and the warm kitchen, not the sight of their parents arguing over money.
When I reached home, my husband’s car was already in the driveway. His mother and sister were no longer with him. I carried our son’s sleeping weight through the front door while my husband helped our daughter upstairs. We moved around each other with the practiced efficiency of parents who knew exactly where the pajamas, toothbrushes, and extra blankets belonged. It was a strange kind of intimacy. We could still manage the details of bedtime without speaking, even though I no longer knew whether I could trust his account of our finances.
Once the children were asleep, I came downstairs and found him sitting at the dining table. He had placed his laptop beside a notepad and a glass of water. I noticed that he had not turned on the television. Ordinarily, when he wanted to avoid a difficult discussion, he would begin watching something and ask whether we could talk another day. Tonight, the room was quiet. He looked up as I entered and said he had been thinking about what his mother had told him.
I sat across from him. He began by saying he never intended to place me in a difficult position. I asked him to be specific about what he believed he had done. He admitted that he had arranged the additional cards without asking and that he had allowed the charges to continue. He said he had expected to manage the payments before the balance became a serious concern. I asked what amount he had considered serious. He couldn’t answer. I wondered how a person who scrutinized grocery receipts could have failed to establish a limit for nearly nineteen thousand dollars in spending.
He told me the expenses had accumulated gradually. A hotel reservation, a restaurant bill, a weekend away, another family occasion. Each individual transaction had seemed manageable when he authorized the arrangement. I understood how expenses could accumulate. I had spent years tracking household costs precisely because small charges could become overwhelming. What I didn’t understand was why he had applied that lesson to my shopping basket while exempting the cards used by his relatives. I asked him to explain the difference, and he stared at his hands.
“I wanted them to enjoy themselves,” he said eventually. I asked whether he wanted our children to enjoy themselves too. He looked irritated and insisted that wasn’t a fair comparison. I reminded him of our daughter’s shoes, the household purchases I had delayed, and the times he had asked me to justify ordinary expenses. He said he thought those discussions were helping us save. I asked how we could be saving money if he was simultaneously permitting additional spending that he had not budgeted or disclosed.
For a long moment, he said nothing. Then he admitted that he had treated the two situations differently. He didn’t offer an explanation that made the contradiction disappear. He said he had wanted to be generous to his mother and sister while keeping our ordinary expenses under control. Hearing him state it so plainly made me feel both relieved and angry. The unfairness had not been something I imagined. He had created separate standards, then expected me to follow the stricter one without knowing another existed.
I opened the folder containing the statements. The paper made a soft scraping sound against the table as I spread out the pages. I showed him the eleven-month sequence and explained that the $18,731 represented the charges I had identified on the additional cards, not necessarily the exact amount still outstanding after payments. He leaned forward and studied the figures. He said some payments had been made from our household checking account. I asked which ones were intended to cover the additional spending. He couldn’t identify them without reviewing the records.
That answer raised another concern. Money leaving our checking account could have paid for groceries, utilities, school expenses, or the credit card. Even if a payment reduced the balance, it did not necessarily mean he had personally funded the spending as he had implied to his mother. I wanted to know whether the ordinary family budget had quietly been absorbing part of those charges while he continued telling me we needed to spend less. He said the payments were complicated because our finances were shared. I told him complicated did not mean impossible to document.
He began opening files on his laptop. The screen illuminated his face as he searched through banking records. I watched him move from one page to another, occasionally stopping to examine a date. For the first time that day, he was doing something that might help establish the facts instead of trying to convince me that the facts were unimportant. I resisted the urge to lean over and direct him. He had created this arrangement, and he needed to take responsibility for explaining it.
After several minutes, he found payments to the account but could not show a separate plan for the additional cards. He pointed out that he had made regular transfers into our shared finances and that those funds contributed to household expenses. I acknowledged that. I was not trying to erase his financial contributions or pretend that I had paid every bill alone. But the existence of shared income did not establish that he had the right to extend credit in my name without telling me. He looked frustrated that each answer seemed to produce another question.
I asked how he had obtained the additional cards in the first place. He said he had used the account information available in our household. I asked whether he had submitted the requests himself. He hesitated, then admitted that he had handled the process. I told him I would verify the details with the issuer because I needed an accurate record of what had happened. He nodded reluctantly. I wasn’t interested in making a legal accusation based on incomplete information. I needed to understand the account access, permissions, and responsibilities as clearly as possible.
He leaned back and said that calling the issuer would make the situation more serious than it needed to be. I told him the situation had already become serious the moment I discovered two additional users and eleven months of charges. My responsibility was to protect the account, not to preserve the appearance that everything was normal. He asked whether I thought he would make another secret arrangement. I answered that I didn’t know what he would do. The fact that I couldn’t answer confidently was part of the problem.
He looked hurt. I recognized the expression and remembered how often it had changed the direction of our disagreements. When I raised a concern, his disappointment would eventually become the central subject, and I would find myself offering reassurance before the original issue had been addressed. I wasn’t willing to repeat that pattern. I told him that trust could not be restored by asking me to stop questioning him. It would require answers that matched the records and behavior that remained consistent after the embarrassment faded.
He asked whether I still considered him a good husband. The question seemed almost impossible to answer in that moment. He was the father of our children, the man with whom I had built a home and shared years of ordinary life. I knew the ways he could be kind and the ways he could be careless. But I also knew what the statements revealed. I told him I wasn’t prepared to reduce our entire marriage to a verdict delivered across the dining table. I was prepared to discuss what had happened and what needed to change.
“Do you want me to apologize?” he asked. I said an apology would matter if he understood what he was apologizing for. He said he was sorry the cards had caused trouble. I shook my head. The cards hadn’t acted independently. They were pieces of plastic issued because someone had arranged them. I told him he needed to acknowledge the choices behind the spending and the information he had withheld. He looked at the statements again, then slowly closed his laptop.
He said he was sorry he hadn’t told me. I waited, and he continued. He admitted that he had known I would want to discuss the arrangement before agreeing to it. He had convinced himself that asking permission would create an unnecessary argument, especially because he believed he could manage the costs. It was the clearest explanation he had offered all day. It also confirmed something I had suspected from the moment I saw the authorized-user list. He had not simply forgotten to tell me. He had decided that involving me would make his plans harder to carry out.
I asked whether he understood why that distinction mattered. He stared at me for a long time before answering. “Because you might have said no,” he said. I nodded. He looked down at the papers. “And I didn’t want you to.” The admission was quiet enough that I almost missed it. There was no shouting, no dramatic confession, and no attempt to shift responsibility to his mother. He had finally acknowledged that he wanted the benefits of my consent without giving me the opportunity to decide.
I sat back in my chair. For eleven months, I had tried to meet financial expectations I believed we had established together. I had accepted his criticism, changed my habits, and delayed purchases because I thought we were protecting the same future. Now I understood that he had reserved the right to make exceptions for himself without telling me they existed. The money was substantial, but the damage reached beyond the balance. He had used my trust to avoid a conversation in which I had an equal right to participate.
He reached toward me across the table. I didn’t pull away sharply, but I didn’t take his hand either. I told him I needed time to decide what his admission meant for our marriage. In the meantime, the account would remain protected, and I expected him to cooperate with a full review of the charges and payments. He said he would. I wrote down the specific records we needed and placed the paper beside his laptop. He looked at the list without protesting.
It was nearly midnight when we gathered the statements into the folder. The house was silent except for the refrigerator and the occasional sound of a car passing outside. My husband asked whether we could go to bed and begin again in the morning. I told him we could rest, but beginning again did not mean returning to the arrangement we had before. He nodded. I wasn’t certain how much he understood, but I no longer felt responsible for making every difficult truth comfortable enough for him to accept.
At the foot of the stairs, he stopped me. “I really did think I could take care of everything,” he said. I looked at him, remembering the hotel bill, the eleven months of charges, and the small purchases I had been made to explain. “That’s part of what went wrong,” I answered. “You decided you were entitled to take care of everything without telling me what you were doing.” He didn’t argue. I went upstairs knowing the next morning would require more than another conversation. We would have to compare his account of events with the records he could no longer ask me to ignore.
END PART 9
PART 10 TITLE: The Next Morning, the Account Statements Answered Questions My Husband Had Avoided and Revealed What His Promises of Repayment Really Meant
I woke before the alarm, with the pale light of morning spreading across the bedroom wall. My husband was still asleep beside me, one arm folded beneath his pillow. For a moment, the room looked exactly as it had the morning before the vacation. Nothing in the furniture or the neatly folded clothes suggested that our marriage had changed. Then I remembered the statements on the dining table and his admission that he had avoided asking because he knew I might refuse. The familiar room no longer felt entirely familiar.
Downstairs, I filled the kettle and opened my laptop. The folder was where I had left it, beside his notepad. I spread the eleven monthly statements across the table and began arranging them by date. I wanted the sequence clear before I contacted the card issuer. The first additional-user charges appeared almost a year earlier, followed by a regular pattern of lodging, meals, travel expenses, and purchases. Some months contained relatively modest amounts. Others showed larger clusters of transactions. Together they formed a record that could no longer be dismissed as occasional generosity.
I made three separate columns on a sheet of paper. The first recorded spending associated with each additional card. The second recorded payments posted to the account during the same period. The third was reserved for questions requiring clarification. I had learned the previous evening that a payment on a credit card did not necessarily reveal who had funded it or which purchases the payer intended to cover. That distinction was important. I wasn’t going to confuse the total spending with the current balance or assume that every payment represented money my husband had contributed independently.
Our daughter came downstairs while I was writing. She was wearing pajamas and carrying the little bag of corn my mother had packed. She asked whether we could cook some for supper. I told her we could and placed it on the kitchen counter. Then she noticed the papers on the table. “Are you doing bills again?” she asked. I said yes. She sighed with the impatience of a child who believed adults wasted far too much time on boring things. I smiled and asked whether she wanted breakfast before her brother woke up.
I made oatmeal and cut fruit while the children talked about the farm. Our son wanted to know whether Grandpa had delivered all the corn from the previous day. Our daughter wondered whether the crooked ear she had found was still in the basket. They had concerns appropriate to their ages, and I intended to preserve that as much as I could. They were not responsible for understanding debt, marital trust, or why their father had returned from his vacation before it began.
My husband came downstairs after the children finished eating. He looked at the statements, then at the breakfast dishes. “You’ve started already,” he said. I told him I wanted to organize everything before calling the card issuer. He asked whether we couldn’t have coffee together first. I said he was welcome to make some and sit with me. He seemed uncertain whether I was being friendly or dismissive. I wasn’t trying to send a hidden message. I simply had work to do, and I didn’t want another morning to disappear into arguments about whether doing it was necessary.
After the children settled in another room, I contacted the card issuer using the number provided through my account. I verified my identity and explained that I had discovered two additional authorized users whose access I had not knowingly approved. I asked the representative to explain the account’s status, the available records, and the steps required to prevent further use. My husband sat across from me, close enough to hear my side of the conversation but without participating. I had decided to make the call myself because the account belonged to me.
The representative confirmed the additional cards had been frozen and explained the available options for removing authorized users and strengthening access to the account. I asked about recurring payments, saved card information, and electronic alerts. I wanted to avoid assuming that possession of the physical cards was the only way another transaction might occur. The representative described the protections available and helped me begin the appropriate changes. I wrote down the confirmation details carefully. Whatever happened in my marriage, I wanted my financial account secured through the issuer rather than through a promise made at the dining table.
I also asked about the original requests for the additional cards. The representative explained what information could be reviewed and what might require a separate inquiry. I did not receive a complete history of every step taken during the application process. I was careful not to turn an incomplete answer into a conclusion. I had my husband’s admission that he arranged the cards without asking me, and I had the statements showing how they had been used. The issuer’s records would help establish the administrative details, but they would not settle the larger question of why he had chosen secrecy.
When the call ended, I updated the account password and reviewed the notification settings. I wanted transaction alerts and statements reaching me directly. My husband watched as I worked, occasionally shifting in his chair. Finally, he asked whether I was planning to keep him away from all our finances. I told him I was separating access to my personal credit from our shared household responsibilities. Those were not the same thing. We could discuss joint bills openly without granting anyone unrestricted control over an account for which I was personally liable.
He said he understood, although his tone suggested he considered the distinction unnecessary. I asked him to imagine discovering that I had arranged spending privileges for relatives on an account in his name. He looked away before I finished the question. I didn’t repeat it. He had heard the comparison enough times. What mattered now was whether he could apply it to his own behavior without requiring me to walk him through the unfairness every time.
By late morning, I had organized the charges into a clearer sequence. The transactions associated with the additional cards totaled $18,731. The failed $4,800 hotel payment remained separate because it had not been successfully charged. The statements also showed payments to the account, but their presence did not answer who had ultimately borne the cost. I noted the dates and amounts and compared them with the records my husband had agreed to provide. I was less interested in producing a dramatic total than in establishing an accurate picture of the financial consequences.
He opened our shared checking history beside me. We compared the account payments with transfers and regular household expenses. Some payments were easy to identify. Others required closer examination. The records suggested that money from our shared checking account had been used to reduce the credit balance during the same period the additional cards were active. I couldn’t assign every dollar of those payments to particular purchases, but I could see why the distinction mattered. My husband had told his mother he was paying for her expenses. Shared household funds were not the same as a separate fund he had saved for that purpose.
I asked whether he had ever set money aside specifically for the travel spending. He said he had expected his income to cover it. I asked whether there was a separate savings account or budget category we should review. He shook his head. The plan, as far as he could explain it, had been to keep making payments while allowing the purchases to continue. I looked at the statements again. He had treated available credit and future income as though they were already money he could offer. Then he had described the resulting obligations as manageable because he intended to manage them.
“Did you ever calculate the total before I showed you?” I asked. He said he had checked the account periodically but hadn’t added the additional-user transactions separately. I asked why not. He answered that the balance changed as payments and purchases were posted. That was true, but it did not explain why he had never established a limit. I reminded him that when I bought groceries, he wanted to know whether each item was necessary. For his mother’s travel, he had apparently relied on the hope that everything would somehow fit into our finances.
He leaned back and rubbed his temples. “I know it looks bad,” he said. I told him the problem wasn’t how it looked. It was how the spending had been arranged and what it had required from everyone else. He said he had been trying to be a good son. I didn’t question whether he loved his mother. I questioned why he believed demonstrating that love justified withholding information from his wife. There was room in our family for generosity, but not for generosity financed through obligations imposed on someone who had not consented.
His mother called shortly after lunch. I stepped into the quieter end of the kitchen to answer. She asked whether I had contacted the card issuer and whether her access had been removed. I told her the account protections were being addressed and that I would confirm the final status when the administrative steps were complete. She said she understood. Then she asked about the transaction list. I told her I was preparing a copy of the charges linked to her card, with any unrelated account information excluded.
She seemed relieved that I was willing to separate the transactions. She said she wanted to identify the purchases she recognized and check her own records before discussing responsibility for them. I thanked her. She paused and asked whether her son had been cooperative that morning. I told her he had provided some account information, although we still had questions to resolve. She didn’t ask me to excuse him. Instead, she said she had spent the night thinking about the times he had insisted on paying for meals and hotel stays. She had believed he was being generous from resources he controlled.
“I should have asked more questions,” she said. I told her she hadn’t been given the full explanation either. She acknowledged that but said she still wanted to examine her own choices. I found myself respecting the seriousness with which she approached the problem. She wasn’t trying to erase the past by declaring herself innocent of every misunderstanding. She wanted to know what she had spent, what she had assumed, and what she could responsibly do next. It was more than my husband had offered before being confronted.
After the call, my husband asked what his mother had said. I told him she wanted the records and intended to review them. He looked uncomfortable. “She’s going to blame herself,” he said. I answered that I had not blamed her for arranging the account because the evidence didn’t show she had done so. But she was entitled to understand how it had been used, and she had the right to consider her own response. He asked whether I could tell her not to worry about the money. I said I would not make promises about obligations we hadn’t yet reconciled.
He looked at me as though I had become unnecessarily rigid. I explained that vague reassurance was part of how we had arrived at this point. He had told everyone the expenses were covered without establishing exactly how. Now he wanted me to give the same kind of assurance to his mother, despite having no reliable basis for it. I wasn’t going to repeat the mistake simply because a precise answer felt uncomfortable. We could examine the records, identify responsibilities, and discuss repayment based on actual numbers.
His sister called later that afternoon. She was quieter than usual and began by apologizing for how the previous day had unfolded. She said she hadn’t realized the cards were connected to my personal account and had assumed her brother was handling everything. I told her I believed she needed to understand the records before making any further statements about the charges. She agreed and asked whether she could receive the transactions associated with her card. I said yes, once I had verified them and removed unrelated details.
Before ending the call, she said something that stayed with me. She told me she had always thought her brother was more financially comfortable than he appeared. When he paid for trips and dinners, she assumed he had chosen those expenses because he could afford them. Hearing him insist that our household needed to economize had never seemed directly connected to the generosity she received. She had not seen the two realities beside each other until the farmyard confrontation. Neither had I, even though I lived in the household where the restrictions were imposed.
After both calls, I returned to the dining table. My husband was looking through the statements again. He asked whether his mother and sister were angry with him. I said they were trying to understand what had happened. He seemed more troubled by their disappointment than by the financial records. I recognized the temptation to comfort him and tell him that everyone would eventually move on. Instead, I asked whether he had finished identifying the payments. He shook his head and returned to the figures.
The afternoon passed in a series of small discoveries. A payment date matched a transfer from our shared checking account. Another charge corresponded to a weekend his mother and sister had traveled. Several entries required further verification because the merchant descriptions were not enough to establish exactly what had been purchased. I made notes instead of assumptions. My husband occasionally remembered a trip or restaurant and supplied details. At other times, he said he couldn’t recall. I wrote that down too.
What disturbed me most was not any particular hotel or restaurant. It was the absence of a coherent plan. My husband had imposed strict expectations on ordinary household spending, yet the additional cards had been allowed to operate without the same review. He had not established a separate fund, a clear reimbursement schedule, or even a firm spending limit that he could explain. He had depended on credit being available and on future payments somehow keeping pace. When that became difficult, he had continued speaking to me as though thrift in the grocery store was the solution.
I told him that our future budget would have to be based on complete information. That meant reviewing joint obligations, identifying personal accounts, and agreeing on what spending required prior discussion. He asked whether I intended to monitor every purchase he made. I told him I wanted transparency, not surveillance. Ordinary individual choices didn’t need a committee meeting. Extending credit to other people, concealing substantial spending, and shifting obligations between accounts certainly required consent. He seemed to struggle with the idea that there could be privacy without secrecy.
He asked whether I would ever trust him to manage money again. I said that question couldn’t be answered with a promise made during one afternoon. Trust would depend on whether his records were complete, whether he accepted responsibility for the charges, and whether he respected boundaries when they became inconvenient. He looked down at the statements. I saw him beginning to understand that there was no single sentence he could say to restore what had been damaged.
As evening approached, I gathered the papers into separate groups. The charges associated with his mother’s card went into one folder. Those associated with his sister’s card went into another. The payments and outstanding questions remained in a third. I kept the complete original statements secure. The work was tedious, but it felt different from the months I had spent trying to justify household expenses. I was no longer producing records to satisfy someone else’s criticism. I was using them to make decisions based on facts.
My husband offered to help prepare dinner. I accepted. We worked in the kitchen together, cutting vegetables and heating the corn my daughter had brought home. He asked where the serving bowls were, even though he had lived in the house for years. I showed him the cupboard without comment. It was a small moment, but it reminded me how unevenly ordinary responsibilities could become distributed when one person assumed the other would always take care of them. The account had exposed a financial problem, but I was beginning to notice the habits surrounding it.
The children came in, drawn by the smell of supper. Our daughter asked whether Dad had enjoyed his vacation. He hesitated, then said it hadn’t gone as planned. She looked disappointed on his behalf and suggested he could visit Grandma another time. He thanked her. I watched his face soften as he spoke to her. He loved our children. I didn’t doubt that. But love had not prevented him from making decisions that affected their household without considering the consequences.
After dinner, he sat with me while I reviewed the payments once more. He pointed to several entries and said he believed they showed he had been covering the additional spending. I traced the corresponding transfers through our checking account. The money had come from funds we were already using for household expenses. That didn’t prove every payment had been misrepresented, but it did undermine his claim that the travel costs had been supported by a separate arrangement of his own.
I explained the distinction carefully. He had been contributing income to our household, and I wasn’t denying that. But he couldn’t simultaneously treat shared money as something he personally controlled for his relatives while telling me our family had to reduce ordinary spending. If the account was going to be repaid from household resources, that decision needed to be discussed openly. If he had promised to pay personally, he needed to identify how he intended to do it without quietly transferring the burden back to us.
He looked at the numbers for a long time. Then he said, “I never really separated the two.” I asked whether he meant his personal promises and our shared financial obligations. He nodded. The admission was important because it explained how he had been able to tell his mother he was paying while treating the resulting balance as part of our ordinary household finances. He hadn’t simply failed to calculate the cost. He had blurred the difference between money he could offer and money we were both responsible for protecting.
I closed the folder. We had not settled the balance, and there were still records to review. The existing debt would need to be handled, and the damage to my trust remained. But the central financial contradiction was finally visible. My husband had been presenting shared resources as though they were entirely his to distribute, while treating my ordinary purchases as expenses that required his approval. I told him that arrangement would not continue. He did not argue, but neither did I mistake his silence for proof that he understood everything.
Before going upstairs, I placed the folders in a locked drawer and checked the account one last time. The additional cards remained blocked, and the access changes were underway. I no longer felt compelled to wonder whether another vacation purchase would appear overnight. The practical work had given me a measure of control, but it hadn’t answered the harder question waiting beyond the statements: whether my husband could build a relationship based on decisions we actually made together, rather than choices he made and expected me to finance afterward.
END PART 10
PART 11 TITLE: When His Mother Began Checking Every Receipt, My Husband Could No Longer Pretend That Generosity Had Cost Our Household Nothing
Three days after the interrupted vacation, a message arrived from my mother-in-law containing several photographs of receipts. She had laid them on a dark wooden table before taking the pictures, straightening each one so the printed dates and merchant names could be read. Some were slightly faded, but others were clear enough to compare with the credit card statements. She wrote that she had found them in an envelope with travel documents and wanted to make sure the purchases were assigned to the correct card.
I opened the photographs on my laptop and began checking them against the transaction list. The process was slow. A few amounts matched immediately, while others required me to compare dates, merchant descriptions, and the details of the trips she remembered. I made notes where the records appeared consistent and left questions beside entries I could not verify. For months, these expenses had existed outside my understanding of our household finances. Now they were becoming individual decisions again, each connected to a particular place, date, and purchase.
My mother-in-law called while I was working. She asked whether the photographs were useful. I told her they were and thanked her for keeping the receipts. She sounded uncomfortable. She said she had never imagined I would need to examine them, and that she had saved most of them only because she sometimes needed to check travel expenses afterward. I told her I wasn’t interested in making her feel ashamed of every meal or hotel stay. I wanted to understand what had happened and who had agreed to what.
She was quiet for a moment. Then she said she had spoken to her daughter about the additional cards. The conversation had been difficult because both women felt they had accepted an arrangement without understanding its consequences. She explained that her son had always presented the expenses as something he could comfortably afford. She had never thought to ask whether his wife knew about the account. “I believed he was being generous,” she said. “I didn’t know his generosity depended on keeping you uninformed.”
I listened without interrupting. I had been angry with both women when I first discovered their names on my account. That anger had been understandable, but the farmyard conversation had revealed important differences between what I assumed and what they knew. The statements showed their purchases. They did not prove they understood whose credit was being used. My husband had encouraged them to believe he was taking care of everything. Recognizing that distinction did not excuse the spending, but it changed how I approached them.
She asked whether I wanted her to speak to my husband about repayment. I told her he and I were already reviewing the financial responsibility. I appreciated her willingness to discuss her own purchases, but I didn’t want him to escape his obligations by transferring every difficult conversation to his mother or sister. He had arranged the additional cards and concealed the arrangement. Whatever the three of them eventually agreed among themselves, he needed to explain his decisions to me directly.
My mother-in-law agreed. She said she had been thinking about the hotel and the way he demanded that I unlock the card. At the time, she had believed the payment failure was an inconvenience that could be corrected with one phone call. Only later had she understood that I was being asked to authorize another substantial charge after discovering months of spending I had never approved. She admitted that if she had known the full circumstances at the hotel, she would not have wanted the payment made through my account.
That admission brought an unexpected sense of relief. During the original call, my husband had used his mother’s discomfort as a reason I should surrender my objection. He had made me responsible for preventing her embarrassment, even though I hadn’t arranged the cards or booked the hotel. Hearing her say that she would have refused the payment herself gave the incident a different shape. The inconvenience had been real, but it did not create an obligation for me to finance it.
After we ended the call, I continued organizing the receipts. My husband was at work, and the house was unusually quiet. The children had gone to school, leaving their shoes beside the door and their breakfast dishes drying on the rack. I thought about how much of family life consisted of details nobody outside the household noticed. School forms, groceries, lunches, clothing, appointments, and the endless small expenses that made ordinary days possible. Those costs had been subjected to intense scrutiny while the additional cards remained almost entirely outside our conversations.
I opened the old grocery records I had kept during the eleven months in question. I wasn’t trying to calculate every dollar I had saved. I wanted to understand how much of my behavior had changed because I believed our finances were under pressure. The notes reminded me of meals I had planned around discounts, purchases I had postponed, and evenings when I had sat at the kitchen table trying to make the next week’s spending fit within the limits my husband insisted were necessary. The effort had become so routine that I had almost forgotten how much attention it required.
I found a list from one month in which I had divided necessary purchases from items we could wait to buy. Our daughter’s shoes appeared near the top. I remembered the argument over their price and the embarrassment of explaining why I couldn’t delay replacing them any longer. I stared at the list for several minutes. There was nothing unreasonable about planning carefully or finding ways to save. What hurt was realizing that I had been making those decisions without access to the same financial information my husband possessed.
That evening, my husband returned home and found the receipts beside my laptop. He looked at them and asked whether his mother had sent more information. I said she had. He picked up one photograph and studied it. “She’s really going through everything,” he remarked. I told him she was trying to identify her purchases accurately. He seemed uncomfortable that she had taken the task seriously. I wondered whether he had expected everyone to promise repayment, apologize, and then quietly forget about the details.
He asked whether the information changed anything. I said it helped verify charges and distinguish transactions. He asked whether we were getting closer to knowing how much each person should cover. I told him the records would support a fair discussion, but I was not prepared to assign obligations based on guesses. Then I asked whether he had completed the list of payments and transfers he promised to review. His expression changed. He said he had been busy at work and hadn’t finished.
I looked at him without speaking. He seemed to realize that the answer was inadequate. His mother had searched through old receipts, his sister had begun checking her records, and I had spent hours reviewing statements. He was the person who arranged the cards, yet he was still treating the accounting as something that could wait until it became convenient. I told him I wasn’t willing to carry the entire burden of reconstructing decisions he had made without me.
He sat down and opened his laptop. For nearly an hour, we worked through the payment history. He identified transfers he remembered making and admitted when he couldn’t connect them to specific charges. I appreciated the moments when he simply said he didn’t know. It was a change from the confident explanations he had offered in the farmyard. The uncertainty was frustrating, but it was at least honest. A record marked for further review was more useful than another assurance that everything had been handled.
At one point, he stopped on a payment and said it should count as money he had contributed toward the additional spending. I asked where the funds had come from. He traced the transfer back to our shared checking account. I reminded him that the money in that account supported the entire household. He objected that his income had helped fund it. I agreed. My income and financial decisions had also supported our shared expenses, and the account existed to serve family obligations we understood together.
He said he felt as though nothing he contributed was being recognized. I told him I recognized his work and his financial contributions. What I would not accept was the idea that contributing to a shared account gave him sole authority to decide which relatives could spend against my personal credit. He had been acting as though joint resources were available for promises he made independently, while my purchases required discussion and restraint. The problem was not that he earned money. It was that he had claimed decision-making privileges he did not extend to me.
He closed his eyes briefly and said he was beginning to understand why I was angry. I asked what he understood. He answered that he had made commitments using money and credit that weren’t solely his to control. He had expected me to accept the consequences afterward. It was the clearest statement he had made without being led through each detail. I didn’t congratulate him. The realization mattered, but it was not a completed repair. It was a starting point.
The following afternoon, his sister sent her own notes. She identified several restaurant and travel charges she remembered and marked others as uncertain. She explained that some purchases had occurred when she and their mother were together, which made it difficult to determine who had benefited from a particular transaction. I appreciated that she hadn’t tried to assign everything neatly without evidence. Her notes were imperfect, but they helped me distinguish what could be confirmed from what remained unclear.
When I showed the information to my husband, he asked whether his sister had offered to pay anything. I told him we hadn’t established a final arrangement. He seemed disappointed. I asked why he was looking to her for immediate reassurance when he had told both women that the expenses were already covered. He said it would help if everyone contributed. I agreed that contributions could be discussed fairly, but I reminded him that he couldn’t solve his concealment by making the people he misled responsible for explaining it to me.
He stared at the table. “I thought they’d be happy,” he said. I asked what he meant. He explained that he had wanted his mother to enjoy travel without worrying about the price and his sister to feel included. He liked being able to arrange things and tell them not to think about money. I could hear the affection behind the explanation. It wasn’t entirely false. He had wanted to make people happy. The trouble was that he had used another person’s financial responsibility to create that feeling of generosity.
I asked whether he understood the difference between offering something freely and promising something someone else would have to provide. He said he did now. Then he added that he had never expected the spending to become so large. I told him unexpected growth was one reason responsible people checked balances and limits. He had demanded exactly that vigilance from me. If an expense mattered enough to impose on our household, it mattered enough to discuss before it was incurred.
That weekend, we sat down to review our regular budget without the additional cards included as available spending tools. I brought our household bills, the school calendar, and the expenses I could reasonably anticipate over the next several months. My husband brought the income and transfer records we needed. We worked through necessities first. Neither of us could predict every future cost, but we could distinguish obligations from optional expenses. For the first time in months, I didn’t feel I was being graded on whether I had found the cheapest possible answer to every household need.
When we reached discretionary spending, my husband became visibly uncomfortable. He had previously treated his own choices as matters of judgment and my choices as items requiring approval. Now I wanted us to agree on a standard that applied to both of us. We discussed what each person could spend independently, what required consultation, and how we would handle requests to help relatives. I wasn’t asking permission to control him. I was establishing that neither of us could make major commitments on behalf of the other without consent.
He asked whether we would still be able to help his mother. I told him we could discuss assistance when there was a real need and a clear plan. That had never been the issue. My parents had needed help with their harvest, and I had offered time and effort we could provide without creating an undisclosed debt. His mother might sometimes need help too. But paying for travel through an account she believed belonged to him was not the same as agreeing together to support her.
We also discussed the children. He acknowledged that he had sometimes been too quick to dismiss purchases I considered necessary. I told him the damage wasn’t confined to the price of a pair of shoes. When every purchase became a defense of my judgment, I had begun to question whether my ordinary decisions were reasonable. He listened without interrupting. I couldn’t tell whether he understood the full effect yet, but he was finally hearing it without turning the conversation into a complaint about my tone.
During a break, our son appeared at the doorway holding a school notice. He needed us to sign a form for an upcoming activity. My husband took the paper, read it, and asked me whether we had already discussed the small expense attached to it. I told him we hadn’t. He looked at the amount, then at me. For a brief moment, I could see the old habit returning: the assumption that I should justify why the children needed something. Instead, he asked whether we could fit it into the budget. We checked, agreed, and signed.
It was a small exchange, almost too ordinary to mention. Yet it represented the difference I had been trying to describe. We had made a decision together, using information both of us could see. Nobody had to defend a child’s needs as though they were evidence of irresponsibility. Nobody had to pretend the expense didn’t exist. I did not mistake one conversation for a transformed marriage, but I recognized that shared decision-making was possible when my husband chose to participate rather than command.
Later that evening, he asked whether I had decided what I wanted from him beyond the financial review. I told him I needed evidence that the changes would last. I needed him to stop using guilt when I disagreed, to respect my control over personal accounts, and to take responsibility for repairing the obligations he had created. I also needed time. He asked how much. I said I couldn’t assign a deadline to trust as though it were a bill with a due date.
He seemed discouraged, but he didn’t argue. He admitted that he had hoped the account review would give us a clear amount to repay and a way to put the problem behind us. I explained that the balance was only one part of what had happened. Even if the account were paid in full, I would still remember that he had deliberately excluded me from decisions involving my own credit. Paying money back could address financial harm. It couldn’t automatically restore confidence in his honesty.
He sat quietly for a while, then said he would continue gathering the records and work with me on a repayment arrangement based on verified amounts. I told him that was necessary. I did not promise forgiveness in return. His responsibilities existed because of his actions, not because I owed him a particular emotional response once he began correcting them. He nodded slowly, as though the distinction was difficult but unavoidable.
Before we went upstairs, I checked the secured account again. There were no new charges associated with the additional cards, and the protections I had arranged remained in place. The remaining financial work was substantial, but at least the spending had stopped. My mother-in-law and sister-in-law were reviewing their records. My husband had begun acknowledging the difference between his promises and our shared obligations. None of that guaranteed a particular outcome for our marriage, but it made the next decisions possible.
I placed the statements back into their folders and closed the drawer. My husband stood beside the table, looking at the empty space where the papers had been spread. He asked whether we could plan something enjoyable for the children once our finances were clearer. I told him we could discuss it together when we knew what we could responsibly afford. He nodded. This time, he didn’t reach for a card or announce that everything was already taken care of. He understood that the answer belonged to both of us.
END PART 11
PART 12 TITLE: The Frozen Cards Stopped the Spending, but the Choice I Made Afterward Changed How Our Family Would Handle Trust and Money
The following week, I received confirmation of the changes I had requested for my credit account. The additional cards were no longer available for use, and I had reviewed the access and notification settings with the issuer. I read the confirmation carefully before saving it with the statements. There was no dramatic sense of victory. The existing charges still needed to be reconciled, and the questions about my marriage remained. But I no longer had to wonder whether someone could make another expensive purchase through those cards while I was preparing dinner or taking the children to school.
My husband was in the kitchen when I printed the confirmation. He looked at the page and asked whether the account was finally secure. I told him the protections we had requested were in place and that I would continue reviewing the account. He nodded and returned to his coffee. A few weeks earlier, he would probably have treated my attention to account security as evidence that I distrusted him unnecessarily. Now he seemed to understand that the concern had a factual basis. Whether that understanding would survive future disagreements was something only time could establish.
The dining table had changed its purpose over the previous several days. It was still where we ate breakfast and helped the children with homework, but it had also become the place where we examined our finances without pretending uncertainty was the same as safety. We had lists of ordinary bills, records of payments, and questions about transactions connected to the additional cards. The figures were sometimes tedious to review, yet their exactness was useful. They did not become kinder or harsher depending on who was speaking. They required us to deal with what had actually happened.
My husband’s mother and sister continued comparing their receipts and memories against the charges. Neither woman claimed that every purchase could be identified immediately, and I appreciated their willingness to leave uncertain items unresolved until more information was available. They understood that the amount of spending was substantial and that the financial responsibility could not be assigned fairly through vague recollections. Their cooperation mattered, but it did not erase the fact that I had learned about their access only after eleven months of transactions.
One evening, my mother-in-law called and asked whether I was still angry with her. I was standing near the kitchen window, watching our son carry a ball across the yard. I considered her question before answering. I told her I had been angry when I first discovered the cards because I believed everyone involved understood exactly whose account was being used. The conversation at the farm had changed that understanding. I still needed to deal with the charges, but I no longer believed she had knowingly participated in the concealment in the way I had initially feared.
She seemed relieved, though she did not ask me to forget the incident. She said she had been embarrassed to discover how confidently she had accepted her son’s assurances. When he told her a trip was covered, she had believed him. When he offered the card, she had assumed the financial arrangements belonged to him. She had never expected that I would discover the spending by opening an account statement the night before his vacation. “I should have asked whose money it was,” she said. I answered that he should have told us both.
She agreed. Then she said something I had not expected. She told me she had always been proud of how generously her son treated the family, but now she realized she had praised the result without knowing what it required of someone else. Her voice was subdued. She wasn’t asking me to comfort her. She was acknowledging that a gesture could look generous to the person receiving it while placing an unseen burden on the person paying. I had lived with that contradiction for nearly a year without knowing its source.
After we ended the call, I remained by the window for several minutes. I thought about how easily a family could develop habits nobody examined. My husband was the generous son who arranged trips. His mother was grateful for his attention. His sister accepted the conveniences he offered. I was the practical wife who kept the household running and found ways to spend less. Each role had seemed familiar enough that nobody questioned what supported it. The credit card statements had revealed the financial consequences of allowing those assumptions to remain separate.
My husband came into the kitchen and asked what his mother had said. I told him she was still sorting through the transactions and thinking about how the cards had been presented to her. He looked down. “I didn’t mean to make her feel foolish,” he said. I believed him. He had probably imagined that providing the card would make her feel cared for, not embarrassed. But the effect of a decision did not disappear because the intention had been different. I told him that honesty would have spared her much of what she was now experiencing.
He nodded, then asked whether I thought his mother would ever look at him the same way again. I told him I couldn’t answer for her. She had heard his explanation, seen the records, and made her own judgments. He would have to speak with her directly and accept that rebuilding her trust might take time too. I noticed how accustomed he had become to asking me to predict and manage other people’s reactions. In the past, I might have offered to call her and smooth things over. This time I left that responsibility with him.
He sat at the kitchen table and looked at the budget we had prepared. He said he was beginning to see how many assumptions he had made about our finances. He had considered the money flowing through our household as a resource he could allocate according to his judgment, even when his choices created obligations in my name. He had expected me to economize without understanding the spending he was approving elsewhere. He did not describe himself as a villain or ask me to excuse him because he had meant well. He simply acknowledged the contradiction.
I told him that acknowledgment was important, but it was only part of the work. We still needed to determine how the existing obligations would be addressed. We needed to avoid further unauthorized access to personal accounts. We needed a household budget in which neither person could demand transparency while withholding it from the other. Most importantly, we needed to stop treating disagreement as disloyalty. If I questioned a proposed expense, I wanted the question answered, not turned into an accusation that I disliked his family.
He listened and said he had often interpreted my objections as criticism of his efforts to help his mother. I told him I could understand why he might have felt defensive, but that his feelings did not justify avoiding the conversation. I had never told him he couldn’t love his mother or assist her. I had objected to being excluded from a financial decision that affected me. Had he asked, we might have discussed what we could afford and chosen a reasonable way to help. He had removed that possibility by deciding in advance that my answer would be inconvenient.
Our daughter interrupted us to ask where her school bag had gone. I found it near the stairs, where she had left it after finishing her homework. She thanked me and ran back upstairs. My husband watched her leave. Then he asked whether the children had noticed the tension between us. I told him they had certainly noticed something, although we had tried to keep the financial details away from them. He looked troubled. I reminded him that children didn’t need to understand every adult disagreement, but they deserved a home where the adults handled responsibilities without making them feel responsible for the conflict.
He agreed. We discussed how to respond if either child asked why the vacation had ended early or why their parents seemed preoccupied. I wanted us to give simple, truthful answers without assigning blame or inviting the children to take sides. We could say we were working through an adult financial matter and that the children were not responsible for fixing it. My husband accepted that. It was another small decision we made together, one that required neither of us to control the other’s explanation.
Two days later, I visited my parents’ farm again. The largest part of the harvest had been completed, but there were still crates to clean, equipment to put away, and baskets to sort. My father was checking the storage shed when I arrived. He asked whether I wanted coffee before helping. I said I would have some after we finished the first stack of crates. He smiled and handed me a pair of gloves. The familiar smell of earth and old wood settled around me as I walked toward the packing area.
My mother came outside carrying a towel and a jug of water. She asked whether things were calmer at home. I told her the account had been secured and that we were reviewing the existing charges. She listened while I explained that my husband had begun acknowledging his decisions more directly, though many questions about the future remained. She didn’t ask whether I intended to forgive him. She didn’t tell me to leave or stay. Instead, she asked whether I felt able to make decisions without being pressured to accept explanations that didn’t satisfy me.
I thought about the question while pulling a loose board from a stack of crates. I told her I felt more able to insist on clear answers than I had before. That didn’t mean I knew exactly what our marriage would look like in six months or a year. It meant I no longer believed I had to settle every argument by protecting my husband’s comfort. My mother nodded. “That’s a useful difference,” she said. Then she picked up another crate and carried it toward the shed.
My father joined us and asked whether the children would visit again before the season ended. I said they wanted to, especially our daughter, who had been talking about the harvest all week. He laughed and told me she had worked harder than some adults he knew. I thought of my husband’s remark before the vacation, when he told me that a little work wouldn’t hurt anyone. He had intended it as a dismissal of the effort he expected us to provide. Yet the time at the farm had given the children something valuable, and it had reminded me what responsibility looked like when people shared it openly.
After helping my parents, I sat on the farmhouse steps with a glass of water. The fields stretched beyond the yard, their rows uneven where the harvest had passed. My phone was beside me, and the account notifications were active. I no longer felt the same apprehension when the screen lit up. There were still statements to review and obligations to address, but I had stopped the uncontrolled spending. I had reclaimed the ability to know what was happening to an account in my name.
My husband called while I was sitting there. He asked whether I would be home in time for dinner. I told him I would. He said he had checked the list of upcoming household expenses and wanted to discuss a purchase before making it. The amount was not extraordinary, but it was large enough that we had agreed to consult each other. I thanked him for asking and said we could look at it when I returned. He didn’t demand an immediate answer. He didn’t accuse me of creating unnecessary complications. He simply said he would wait.
When the call ended, I looked across the field and considered how ordinary the exchange had been. It didn’t repair the past. It didn’t erase the $18,731 in recorded additional-card charges or the fact that I had discovered them myself. But it showed what the decision-making process could have looked like from the beginning. A question asked before an obligation was created. Information shared while both people still had a choice. No need for secrecy, resentment, or a confrontation in a farmyard.
I returned home that evening with a small bag of corn and the familiar ache of physical work in my shoulders. My husband was preparing supper, and the children were setting the table. He asked about my parents and whether they had finished putting away the equipment. I told him what we had done. For once, he didn’t make a remark about how inexpensive the farm food must be or how useful the labor was for me. He listened and asked whether my father needed any help with the remaining crates.
I told him there was still some work to do. He said he could assist if my parents wanted him there. I didn’t immediately accept or reject the offer. I told him he could ask them directly. The distinction was small, but important. He had spent months announcing what other people needed and deciding how those needs should be met. Helping my parents was not an opportunity for him to earn forgiveness from me. It was a choice he could make openly, with their agreement, because he genuinely wanted to contribute.
After the children went upstairs, we reviewed the proposed purchase he had mentioned earlier. We looked at the budget, considered the timing, and made a decision together. There was no dramatic conversation about trust. There was simply an expense and the information necessary to decide whether it made sense. I found the ordinary nature of the exchange more meaningful than another elaborate apology would have been. Respect was easier to recognize when it appeared in the decisions people made without an audience.
Later, he asked whether I believed we could move forward. I told him moving forward did not require pretending we had already resolved everything. The financial review was ongoing, and the existing obligations needed responsible attention. His mother and sister were still clarifying their purchases. He had begun taking steps toward accountability, but the changes were too recent for me to know whether they would last. I was not prepared to give him the reassurance he wanted simply because he was uncomfortable with uncertainty.
He seemed disappointed, but he accepted the answer. I told him I wasn’t trying to hold the incident over him indefinitely. I wanted a marriage in which both people understood the obligations they were creating and neither used affection or family loyalty as a reason to conceal substantial decisions. If he wanted to rebuild my trust, he would need to demonstrate those principles consistently. I couldn’t provide the consistency for him. I could only decide how I would respond to what he actually did.
He sat quietly for several minutes. Then he said he understood that repayment alone wouldn’t solve the problem. I asked what else he thought mattered. He answered that I needed to know he would tell me the truth even when he expected me to disagree. He said he had avoided the conversation about the cards because he wanted the arrangement to continue without resistance. I acknowledged that he was finally describing the decision honestly. I did not tell him the admission made everything right.
The following morning, our daughter asked whether we could visit her grandparents again during the next harvest. I told her I hoped so. She smiled and said she wanted to carry a bigger basket when she was older. Our son immediately announced that he would still carry more than she did. Their argument followed us through breakfast, filling the kitchen with the kind of noise I had missed during the tense days after the vacation. I watched them and understood how much I wanted to protect the ordinary life we had built without pretending its problems were insignificant.
That afternoon, I put the remaining account papers in order. The charges were documented, the additional cards had been removed from use, and the household budget was no longer something my husband could present as a list of restrictions applying primarily to me. There were still questions about the precise remaining financial obligation, and I intended to follow them through. I wasn’t interested in declaring victory over my husband’s embarrassment or his mother’s disappointment. I wanted financial arrangements that reflected actual consent and responsibilities that did not disappear behind reassuring language.
I thought again about the first moment I saw those unexpected names beneath the authorized-user section. At the time, I had felt a mixture of disbelief and fear. The account was mine, yet important decisions about it had been made without me. I had wondered how many more purchases would appear and whether anyone would acknowledge what had happened. The situation was not magically resolved, but the central questions were no longer hidden. My husband had admitted he arranged the cards. His mother and sister understood whose account they had used. The records were being reviewed rather than ignored.
What remained uncertain was the future of the trust that had been damaged. I couldn’t promise that time alone would restore it. I couldn’t say that one apology, a repayment arrangement, or a few cooperative conversations would be enough. Those things could contribute to repair, but they could not replace the choices my husband would have to make when telling the truth was inconvenient. I had spent too long trying to anticipate his reactions and prevent his disappointment. That was not a responsibility I intended to resume.
On my next visit to the farm, I found my father beside the packing shed, sorting the last of the usable baskets. He handed me one without asking whether I was prepared to help. I took it and walked toward the remaining crates. The work was familiar now. I knew how the handle would press against my fingers and how the rough boards would catch against my gloves. I knew what needed to be done, why it mattered, and who had asked for my help.
My husband had laughed when he left for his vacation and suggested that hard work would be good for me. He had not imagined that the work would reveal something about the life I had been living. The harvest had demanded patience and effort, but nothing about it was concealed. The crates were heavy. The weather was hot. Everyone could see the task in front of us. When someone needed help, they asked, and the person being asked could decide what they were willing to give.
I lifted another basket and carried it toward the shed. The credit account was protected, but the balance still required attention. My husband was beginning to accept responsibilities he had once tried to explain away, but I was not ready to call our trust restored. Those were facts I could live with while I considered what came next. For the first time in nearly a year, I no longer had to accept a version of financial responsibility that depended on my ignorance. I knew what had happened, and I intended to remain part of every decision that affected my future.
END PART 12